Tag Archives: repossessed cars

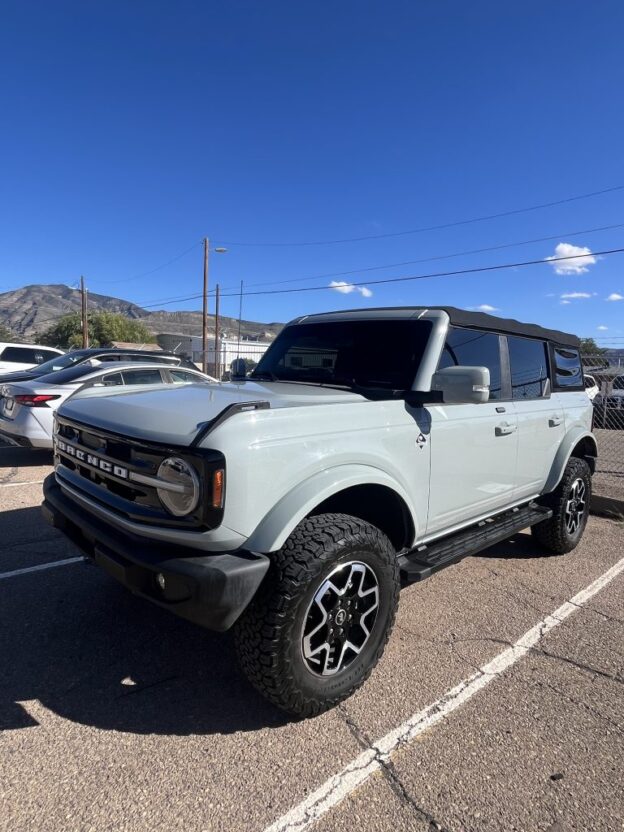
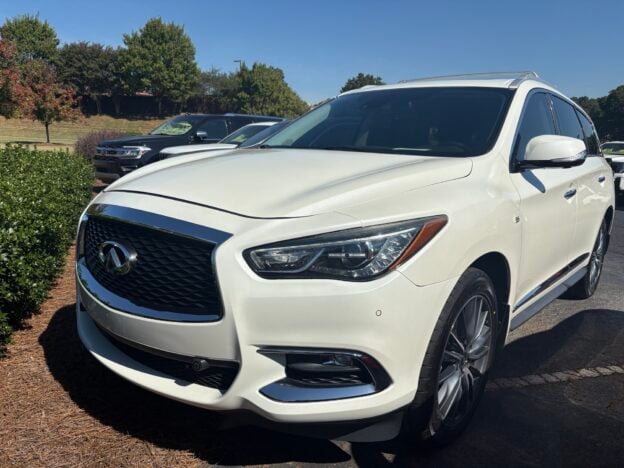
Repo car for sale at a credit union with a 3% interest rate

Can a Repo Car Help You Beat High Auto Loan Rates?

TL;DR: Some banks and credit unions offer special financing on selected repossessed vehicles. Founders Federal Credit Union currently lists specific repos that qualify for 1% or 3% financing, subject to credit union approval. That is a vehicle-specific opportunity, not a rate every buyer or every repo will receive. Compare the written loan terms, vehicle price, condition, fees, and repair costs before deciding.

Borrowing costs are back in the headlines. Freddie Mac’s weekly survey put the average 30-year fixed mortgage rate at 7.28% on October 1, 2026, up from 7.03% the prior week. That is a mortgage benchmark, not an auto-loan quote, but it helps explain why buyers are scrutinizing financing costs. For a vehicle, one option is to look for a bank or credit union repo with a special financing offer attached to that specific listing.

Start by comparing repo cars for sale, then confirm the current price and financing terms with the lender selling the vehicle.

Can a bank or credit union repo come with low-interest financing?

Sometimes. A repossessed car is still a used vehicle, and its loan terms depend on the lender, vehicle, buyer, and offer. The selling institution may finance the purchase, or it may allow you to use another lender. Ask about purchase eligibility and loan eligibility separately; a lender may have different rules for buying a vehicle and borrowing from it.

Founders FCU is a useful example. Its current repossessions page currently shows selected vehicles with notes that they qualify for 1% or 3% financing, subject to credit union approval. Those notes appear on individual vehicle listings, so they should not be read as an offer for every Founders repo or every applicant. Founders also says viewings and test drives are by appointment, and some vehicle listings state that the vehicle is sold as-is with no warranty.

Founders’ general auto-loan rate information lists different APR ranges for ordinary new and used auto loans. Before relying on a special repo listing, ask Founders to confirm in writing whether the stated 1% or 3% is the APR, what term applies, which buyers and vehicles qualify, and whether membership or a down payment is required.

How much could a lower rate change the payment?

The interest rate can make a noticeable difference when the purchase price and loan term are the same. Here is a hypothetical example for $20,000 financed over 48 months with a fixed APR:

Hypothetical APR Estimated monthly payment Estimated total interest
1% About $425 About $411
3% About $443 About $1,249
8% About $488 About $3,436

Under those assumptions, financing $20,000 at 3% instead of 8% would reduce the payment by about $46 per month and the total interest by about $2,187. At 1%, the estimated difference would be about $63 per month and $3,025 in interest. This is an illustration, not a quote from Founders or any other lender. It assumes the listed percentage is a fixed APR and excludes taxes, title, registration, lender fees, insurance, transportation, and repairs. Get the actual APR and term before comparing offers.

Compare the whole deal, not just the advertised rate

A low rate helps only if the vehicle and total purchase cost make sense. Before making an offer, compare:

What to compare What to verify
Vehicle price Compare the asking price with similar year, make, model, mileage, and condition in your area. A repo is not automatically below market.
Financing Confirm APR, term, payment, amount financed, down payment, fees, approval requirements, and offer expiration.
Condition and title Ask whether an inspection or test drive is allowed, review title status, and check the vehicle history when available.
Sale terms Confirm whether the vehicle is sold as-is, the payment deadline, accepted payment methods, taxes and fees, and pickup or transport rules.

Ask the lender: Is this vehicle still available? Does the low-rate offer apply to this VIN? Is the quoted percentage an APR, and for how many months? Do I need to be a member to buy or finance it? Can I use outside financing? Can I arrange an independent inspection before committing?

Founders currently requires appointments for vehicle viewings and test drives. Confirm that process before traveling. Use RepoFinder’s buyer’s checklist for repossessed vehicles to keep inspection, title, payment, and pickup questions organized.

Where can you find bank repo cars with financing offers?

RepoFinder helps shoppers locate current listings and lender sale pages, but the selling bank or credit union sets the price, availability, and loan requirements. Search the RepoFinder search tool for current inventory, browse the directory of banks and credit unions that sell repo cars, or start with repo cars near you.

Because Founders serves buyers in the Carolinas, shoppers can also browse South Carolina repo listings and North Carolina repo listings. For more background on the lender, see our guide to Founders Federal Credit Union repos. Inventory may appear on the lender’s page, on RepoFinder, or in both places, so check the original listing for the latest terms.

Frequently asked questions

Can anyone get 1% or 3% financing on a repo car?

No. A listing’s financing note is subject to the lender’s approval and may apply only to a particular vehicle, borrower, loan amount, or term. Ask the lender for a written quote.

Does a low-rate repo automatically cost less than a dealer car?

No. Compare the vehicle’s price, condition, fees, and likely repair costs as well as the interest. A low payment can still accompany a poor overall deal if the vehicle costs too much or needs major work.

Can I use financing from another bank or credit union?

Possibly, but the seller sets its payment and closing rules. Ask whether outside financing is accepted and whether the funds can arrive by the lender’s deadline.

Are repo cars sold with a warranty?

Some are sold as-is, and terms vary by listing. Founders’ page marks some vehicles as-is with no warranty. Confirm the terms for the exact vehicle and arrange an inspection when permitted.

Start with the listing, then confirm the loan

A bank or credit union repo can be a way to find a vehicle with a special financing offer, but the rate alone does not prove it is the best deal. Compare the full cost, inspect the vehicle, and get the lender’s exact APR, term, and eligibility rules in writing before you commit.

BROWSE REPO CARS FOR SALE

Repossessed vehicle offered through a Tennessee credit union

Trust Federal Credit Union Repos for Sale in Tennessee: How the Auction Works

TL;DR: Trust Federal Credit Union in Chattanooga occasionally offers repossessed vehicles for direct sale. Its page says bidding typically lasts two to three weeks, the highest bid is subject to an undisclosed reserve, and high bids are generally updated each business day. Confirm the vehicle’s terms with Trust before bidding.

If you are searching for Trust Federal Credit Union repos for sale, start with TRUST FEDERAL CREDIT UNION’S VEHICLES FOR SALE. Trust FCU says it occasionally offers repossessed vehicles that meet its quality standards for direct sale instead of sending them to auction. It calls the process a direct-sale auction and provides an Auction Bid Form.

Inventory is occasional, so the page may not always show a vehicle that fits your needs. Check the listing for current details, then contact Trust FCU with questions about the specific vehicle and bidding process.

How does Trust FCU’s repo auction work?

Auction detail What Trust FCU says
Availability Repossessed vehicles are offered occasionally.
Typical bidding period Direct-sale auctions typically run for two to three weeks.
Winning bid The highest bid secures the vehicle, subject to an undisclosed reserve price.
Bid updates Current high bids are generally updated at the beginning of each business day.
How to bid Trust FCU links an Auction Bid Form from its vehicle sale page.

The auction page does not explain every step after the form is submitted. Ask Trust FCU to confirm the closing time, whether the reserve has been met, how it notifies the winning bidder, and when payment is due.

For example, if you bid on a vehicle early in its listing period, the posted high bid could change before the auction closes. Trust says high bids are generally updated each business day, so confirm the closing date and final acceptance before arranging payment or pickup.

Because every vehicle is subject to a reserve, the highest visible bid should not be treated as a guaranteed sale. Confirm with the credit union whether the reserve has been met and whether the sale is final.

Does the highest bid always win?

Trust FCU says the highest bid secures the vehicle, but each vehicle has an undisclosed reserve price. The page does not publish that reserve. A high bid may therefore not complete the sale unless the reserve requirement is met.

Before bidding, ask whether the credit union can confirm that the reserve has been met. Also ask when bidding closes and whether a bid can be changed or withdrawn. Do not assume the page updates bids in real time; Trust says high bids are generally updated at the beginning of each business day.

Do you have to be a Trust FCU member to bid?

The vehicle sale page does not say whether membership is required to view, bid on, or buy a vehicle. Ask Trust FCU directly before submitting a bid.

Trust’s membership page says people who live, work, worship, or attend class in downtown Chattanooga may be eligible to join. It also lists family members of current members, Chattanooga Audubon Society members, and employees of certain local companies, including Unum, Cigna, and WestRock.

Membership eligibility and loan approval are separate questions. If you want financing from Trust FCU, ask whether it finances vehicles bought through this direct-sale auction and what membership or loan requirements apply. The vehicle sale page does not promise financing for auction purchases.

What should you check before bidding?

Trust FCU says the vehicles it offers for direct sale meet its quality standards, but the page does not define those standards or provide a general condition, warranty, or inspection policy. Review the information for the individual vehicle and ask questions before bidding.

Confirm:

  • Whether you can inspect or test-drive the vehicle before bidding
  • The vehicle’s title status, mileage, condition, and known mechanical issues
  • Whether the sale is as-is and whether any warranty applies
  • Any deposit, payment deadline, taxes, fees, and pickup requirements
  • Whether the bid form creates a binding offer and whether bids can be changed
  • How Trust FCU handles the reserve and notifies the winning bidder

Do not assume that a bank or credit union repo has a particular title status or is in a particular mechanical condition. Verify the paperwork and inspect the vehicle if Trust FCU allows it. RepoFinder’s buyer’s checklist for repo vehicles can help you organize those questions.

Where can you find more repo vehicles in Tennessee?

Trust FCU’s page is a lender-specific source. To compare other repossessed vehicles around the state, browse Tennessee bank and credit union repos or view the current Tennessee repo inventory.

You can also use RepoFinder Search to look across current listings by state, vehicle type, keyword, and price. For a car-focused search, see repo cars for sale. If you are looking beyond Tennessee, the bank and credit union repo directory links to lenders across the country.

Start with Trust FCU’s current page

Trust Federal Credit Union’s direct-sale process gives buyers a way to bid on certain repossessed vehicles through the credit union. Since inventory is occasional and bids are subject to an undisclosed reserve, check the current listing and confirm the rules for the specific vehicle before committing.

VIEW TRUST FEDERAL CREDIT UNION’S VEHICLES FOR SALE, then compare them with other Tennessee repo listings on RepoFinder.

You can buy a repo car without being a bank or credit union member.

Can You Buy Repo Cars Without Being a Member?

TL;DR: In many cases, you can buy a repossessed car without being a member of the bank or credit union selling it. Some lenders sell repo vehicles directly to the public, while others may require membership for financing or give members priority. Always contact the lender to confirm its rules, inspect the vehicle, verify the title, and understand all purchase costs before paying.

Yes, in many cases you can buy a repo car without being a member of the bank or credit union selling it.

Banks and credit unions repossess vehicles because a borrower stopped making payments on an auto loan. After taking possession of the vehicle, the financial institution typically wants to sell it and recover as much of its money as possible.

That means the lender’s primary goal is usually to complete a legal, straightforward sale. It may not require the buyer to already have an account or loan with the institution.

However, every bank and credit union sets its own rules. Some lenders sell repossessed vehicles to anyone, while others may give members priority, require membership for financing, or use different procedures for accepting offers.

If you are looking for current lender-owned vehicles, you can search RepoFinder’s nationwide repo listings by state, vehicle type, keyword, and price.

Do You Have to Be a Bank Member to Buy a Repo Car?

Usually, no.

Many banks sell repossessed cars, trucks, SUVs, RVs, boats, motorcycles, and other property to the general public. The buyer may not need an existing checking account, savings account, or auto loan with that bank.

Credit unions can be slightly different because they are membership-based financial institutions. A credit union may allow anyone to purchase one of its repossessed vehicles, but it may have separate membership requirements for financing or other services.

Before assuming that membership is required, contact the lender selling the vehicle and ask:

  • Is the repossessed vehicle available to nonmembers?
  • Does the buyer need to open an account?
  • Is membership required only for financing?
  • Are offers accepted from the public?
  • Does the lender use a fixed price, auction, or sealed-bid process?
  • What payment methods are accepted?
  • Is the vehicle sold as-is?

The answer can vary from one lender to another, so buyers should always verify the requirements directly.

You can also browse RepoFinder’s list of banks that sell repo cars to locate financial institutions offering repossessed vehicles.

Why Do Banks and Credit Unions Sell Repo Cars to the Public?

Banks and credit unions are lenders, not traditional car dealerships. They generally do not want to keep repossessed vehicles sitting in storage for months.

Selling the vehicle allows the lender to:

  • Recover money from the unpaid loan
  • Reduce storage and maintenance costs
  • Resolve the borrower’s outstanding account
  • Remove the vehicle from its inventory
  • Convert the repossessed asset into cash

Because the lender is trying to recover money rather than operate a dealership, the purchasing process may be different from buying a vehicle from a dealer.

The lender may list the vehicle at a set price, accept offers, conduct a local sale, or send the vehicle to an auction. When a bank or credit union sells directly to the public, buyers may be able to avoid some dealer markups and auction-related fees.

You can browse current repo cars for sale to see the types of lender-owned vehicles available.

Can Nonmembers Finance a Repo Car?

Possibly, but financing rules are often different from purchasing rules.

A bank or credit union may allow a nonmember to buy a repossessed vehicle with cash, a cashier’s check, or approved outside financing. However, the lender may require membership before offering its own auto loan.

Some credit unions allow a buyer to join before applying for financing. Others may require the buyer to meet geographic, employment, organizational, or other eligibility requirements.

Before making an offer, ask the lender:

  • Does the lender finance its own repossessed vehicles?
  • Can nonmembers apply for financing?
  • Is membership required before applying?
  • What credit requirements apply?
  • Is a down payment required?
  • Can the buyer use financing from another bank?
  • How quickly must payment be completed?

Buyers who need financing should get preapproved when possible. Having financing arranged ahead of time can make it easier to act quickly when a desirable repo vehicle becomes available.

For more information, see Buying and Financing a Repossessed Vehicle at a Bank.

Can You Buy a Repo Car From a Credit Union Without Joining?

Sometimes, yes.

Credit unions commonly sell repossessed vehicles to recover losses from unpaid loans. Some make those vehicles available to the public, even if the buyer is not already a member.

Other credit unions may have different requirements. For example, a credit union might:

  • Allow anyone to submit an offer
  • Require membership before completing the sale
  • Require membership only for financing
  • Give members an early opportunity to purchase
  • Sell the vehicle through a public auction
  • Require the buyer to meet specific eligibility rules

Membership is often easier to obtain than buyers expect, but buyers should not assume that joining is necessary. Contact the credit union and ask about its current repo-sale policy.

RepoFinder helps buyers locate bank-owned cars for sale and other repossessed vehicles offered by lenders throughout the United States.

How to Buy a Repo Car Without Being a Member

The process is usually straightforward.

1. Find a lender-owned repo vehicle

Start by searching current bank and credit union repos by location, vehicle type, make, model, and price.

RepoFinder includes listings for cars, trucks, SUVs, vans, RVs, boats, motorcycles, trailers, powersports, commercial vehicles, and equipment.

2. Review the listing carefully

Look for the vehicle identification number, mileage, asking price, location, photographs, sale deadline, and contact information.

Inventory can change quickly, so a vehicle may sell before the listing is removed.

3. Contact the selling bank or credit union

RepoFinder helps buyers locate the vehicle, but the selling lender controls the final sale.

Ask the lender to confirm:

  • The vehicle is still available
  • The current price
  • The title status
  • Whether there are liens or title issues
  • Whether an inspection is allowed
  • Whether a test drive is available
  • Whether nonmembers may purchase
  • What payment methods are accepted
  • Where the vehicle must be picked up

4. Inspect the vehicle

Most repossessed vehicles are sold as-is. If possible, inspect the vehicle in person or hire a qualified mechanic to examine it.

Check the tires, engine, transmission, warning lights, fluids, body, interior, brakes, electronics, and signs of water damage or neglect.

A repo vehicle is not automatically a salvage vehicle. Repossession generally relates to a loan default, while a salvage title usually relates to major damage or an insurance total loss. Even so, always verify the title and vehicle history before buying.

5. Check the market value

Compare the lender’s price with current values for similar vehicles. Consider mileage, trim level, condition, location, taxes, transportation, registration, repairs, and other purchase costs.

A low asking price does not necessarily mean the vehicle is a good deal if it needs major repairs.

6. Submit an offer or complete the purchase

Depending on the lender’s rules, you may submit an offer, participate in bidding, or pay the listed price.

Follow the lender’s instructions carefully. Ask for written confirmation of the purchase terms, payment deadline, pickup requirements, and documents you will receive.

What Documents Do You Need to Buy a Repo Car?

The requirements vary, but buyers may need:

  • Government-issued identification
  • Proof of insurance
  • Payment in an approved form
  • A signed bill of sale
  • Purchase agreement
  • Title or title-transfer documents
  • Registration paperwork
  • Financing documents, if applicable

Ask the lender which documents will be provided and whether the title is immediately available. If the title is delayed, find out why and how the transfer will be completed.

Are Repo Cars Cheaper When You Buy Directly From a Bank?

They can be, but there is no guaranteed discount.

Banks and credit unions may price repossessed vehicles competitively because they want to sell them quickly. Buying directly from a lender may also reduce dealer markups and certain auction-related expenses.

However, buyers still need to account for:

  • Repairs and maintenance
  • Taxes and registration
  • Transportation or shipping
  • Inspection fees
  • Insurance
  • Possible buyer or administrative fees
  • Financing costs

The best way to evaluate a repo is to compare its total cost with similar vehicles from dealerships and private sellers.

You can also compare local inventory by searching repo cars near you.

Are Bank Repo Cars Safe to Buy?

Many repossessed vehicles can be good purchases, but they should be evaluated like any other used vehicle.

A borrower’s financial problems do not automatically mean the vehicle was abused. Some repos are newer vehicles with ordinary wear and maintenance histories. Others may have been neglected, damaged, vandalized, or stored improperly.

Before purchasing, verify:

  • Vehicle history
  • Title status
  • Mileage
  • Mechanical condition
  • Accident history
  • Outstanding recalls
  • Whether keys are included
  • Whether the vehicle starts and drives
  • Whether personal property remains inside
  • Whether the lender provides any warranty

Never rely only on photographs or a low price.

Final Thoughts

You can often buy a repo car without being a member of the bank or credit union selling it. The key is understanding the lender’s specific rules.

Some financial institutions sell directly to the public. Others may require membership for financing, give members priority, or use a public auction process.

The safest approach is to find the vehicle, contact the selling lender, verify the purchase requirements, inspect the vehicle, confirm the title, and understand every cost before paying.

RepoFinder helps buyers search current repossessed cars and other lender-owned vehicles from banks and credit unions across the country. Start by using the RepoFinder search tool or browse the list of bank repossessed cars.

FAQ

Can I buy a repo car if I am not a bank customer?

Yes, many banks sell repossessed vehicles to the general public. However, each lender sets its own rules, so confirm the requirements before making an offer.

Do I have to join a credit union to buy its repo car?

Not always. Some credit unions allow nonmembers to purchase repossessed vehicles, while others may require membership for the purchase or financing.

Can I finance a repo car without being a member?

Possibly. You may be able to use outside financing, pay cash, or join the credit union before applying for its auto loan.

Are repo cars sold directly by banks?

Some are. Banks and credit unions may sell repos directly, list them through a third party, or send them to an auction.

Does RepoFinder sell the repo cars listed on its website?

No. RepoFinder helps buyers locate current bank and credit union repos. The selling lender controls the price, condition, title, payment terms, and final sale.

Do repo cars have clean titles?

Many lender-owned repos have clean titles, but repossession does not guarantee a clean title. Always verify the title status and vehicle history with the selling lender.

Where can I find repo cars for sale without joining a bank?

You can use RepoFinder to search current repos from banks, credit unions, and other financial institutions. Contact the lender directly to confirm whether nonmembers may purchase.

bank repo shopping

Why Most Repo Car Websites Aren’t Actually Showing You Bank Repos

Why Most Repo Car Websites Aren’t Actually Showing You Bank Repos

If you’ve searched online for repo cars, you’ve probably seen websites promising everything from $100 government vehicles to police seizures, IRS auctions, foreclosures, and repossessed cars all on the same page.

At first glance, it sounds exciting.

But here is the problem: many buyers think they are looking at real bank repos when they are actually being shown auction listings, salvage vehicles, government surplus property, dealer leads, or classified ads.

That difference matters.

Most buyers searching for repo cars are not trying to chase confusing auction hype. They want a real vehicle, a fair price, and a clear path to contact the seller.

They want real bank repos.

Understanding the difference can save you time, money, and frustration.

Want to skip auctions and browse repo cars directly from banks?

RepoFinder helps buyers search current bank and credit union repos, then buy directly from the selling lender.

Not All “Repo” Sites Are the Same

Many websites use the word “repo” as a catch-all term for auctions, seizures, surplus property, salvage vehicles, and classified listings.

That can be confusing for buyers.

Here is the simple difference:

Many Repo Websites Promote

  • Police auctions
  • Government seizures
  • IRS auctions
  • Salvage auctions
  • Dealer auctions
  • Classified listings
  • Lead-generation offers

RepoFinder Focuses On

  • Bank repos
  • Credit union repos
  • Current lender inventory
  • Direct lender contact information
  • No dealer markup
  • Nationwide repo listings
  • Searchable repo inventory

What Is a Real Bank Repo?

A bank repo is a vehicle that was financed by a bank, credit union, or other lender and later repossessed after the borrower stopped making payments.

Once the lender takes possession of the vehicle, it may choose to sell it directly to recover part of the loan balance.

These vehicles often include:

  • Cars
  • Trucks
  • SUVs
  • RVs
  • Motorcycles
  • Boats
  • Commercial vehicles

In many cases, the lender simply wants to recover its money and move the vehicle quickly.

That creates opportunities for buyers who know where to look.

Why Buyers Search for Bank Repos

People are attracted to bank repos because they often offer advantages over traditional used-car lots.

Potential benefits include:

  • Competitive pricing
  • No dealer markup
  • Direct access to the selling lender
  • Transparent ownership history
  • Many vehicles have clean titles
  • Financing may be available through the selling institution

While every vehicle should be inspected before purchase, bank repos have become popular because buyers are dealing directly with the financial institution rather than multiple middlemen.

That is why many shoppers use RepoFinder’s searchable repo inventory to look for current repos from banks, credit unions, and other financial institutions.

The Problem With Many Repo Websites

Many websites use the term “repo” very broadly.

A site may advertise repo vehicles while also promoting:

  • Police auctions
  • Government surplus sales
  • IRS seizures
  • DEA seizures
  • Salvage auctions
  • Dealer auctions
  • Classified listings
  • Foreclosures

These are not the same thing.

A police auction is not a bank repo.

A salvage auction is not a bank repo.

A government surplus vehicle is not a bank repo.

A classified ad is not a bank repo.

Combining all of these categories together can make it difficult for buyers who specifically want lender-direct inventory.

The $100 Repo Car Myth

One of the most common marketing claims online involves “$100 cars” or vehicles selling for pennies on the dollar.

Technically, some auctions may start bidding at very low amounts.

That does not mean desirable vehicles sell for those prices.

In reality, popular cars, trucks, and SUVs attract multiple bidders and often sell closer to market value.

Smart buyers focus on value rather than hype.

A vehicle priced fairly by a bank or credit union can be a much better purchase than chasing unrealistic auction claims.

Bank Repos vs Police Auctions: What’s the Difference?

Bank repos and police auctions can both offer used vehicles, but they are not the same source of inventory.

Bank repos are usually vehicles repossessed by a lender after loan default. Police auctions usually involve seized, abandoned, impounded, or surplus vehicles.

That difference can affect title status, condition, buying process, fees, financing, and who the buyer contacts.

Feature Bank Repos Police Auctions Salvage Auctions
Sold by banks or credit unions Often No No
Direct lender contact Yes No No
Financing may be available Often Rarely Rarely
Clean titles are common Often Varies Often no
Buyer fees Usually lower or none May apply Often apply
Final price Often listed upfront Determined by bidding Determined by bidding

Bank Repos vs Auction Vehicles

Let’s compare the buying experience more directly.

Bank Repos

  • Sold by banks and credit unions
  • Often available with lender contact information
  • Frequently include financing options
  • Commonly have clean titles
  • Pricing is usually straightforward

Auction Vehicles

  • Sold through bidding
  • Final price is unknown until auction ends
  • Buyer fees may apply
  • Salvage vehicles are common
  • Competition can drive prices higher

Neither approach is automatically better.

The key is understanding what you’re actually shopping for.

Why RepoFinder Takes a Different Approach

RepoFinder was built around a simple idea:

Help buyers find repossessed vehicles directly from banks and credit unions.

RepoFinder is not an auction company. RepoFinder helps buyers search current repossessed vehicles from banks, credit unions, and financial institutions nationwide. Buyers can then contact the selling lender directly.

Instead of focusing primarily on auctions, RepoFinder helps users search current repo inventory from financial institutions across the United States.

Buyers can search by vehicle type, state, make, and model while connecting directly with the lender selling the vehicle.

That means less time sorting through unrelated auctions and more time finding actual lender-owned inventory.

For example, buyers can search for repo cars for sale, browse repo trucks, or look for vehicles by state and make using RepoFinder’s search tools.

Search Current Bank and Credit Union Repos

Whether you’re looking for:

  • Repo cars
  • Repo trucks
  • Repo SUVs
  • Repo RVs
  • Repo boats
  • Repo motorcycles
  • Commercial equipment

RepoFinder helps connect buyers with current inventory from banks, credit unions, and other financial institutions nationwide.

The goal is simple:

Search current bank and credit union repos, then buy directly from the selling lender.

Ready to Search Real Bank Repos?

Browse current repossessed cars, trucks, SUVs, RVs, boats, motorcycles, and more from banks and credit unions nationwide.

Search Repo Inventory

Final Thoughts

Not all repo websites are built the same.

Many focus on auctions, government seizures, classified ads, or salvage inventory.

If your goal is to find actual bank-owned vehicles being sold by lenders, it’s important to understand the difference.

Before spending hours searching through auction listings, make sure you’re looking in the right place.

The more directly you can connect with the institution selling the vehicle, the easier it becomes to compare options and make an informed purchase.

That’s exactly what RepoFinder was designed to do.

Frequently Asked Questions

What is a bank repo vehicle?

A bank repo vehicle is a car, truck, SUV, RV, boat, motorcycle, or other asset repossessed by a lender after loan payments were not made.

Are bank repos the same as police auction vehicles?

No. Police auction vehicles usually come from law enforcement agencies, impound lots, or government sources. Bank repos are owned and sold by banks, credit unions, or financial institutions.

Are bank repos the same as salvage auction vehicles?

No. Salvage auctions often include damaged vehicles, insurance losses, and vehicles with salvage or rebuilt titles. Many bank repos are ordinary financed vehicles that were repossessed after loan default.

Does RepoFinder sell vehicles directly?

No. RepoFinder helps buyers search repossessed vehicles from banks, credit unions, and other lenders. Buyers contact the selling institution directly.

Are repo vehicles cheaper than dealer vehicles?

Many repo vehicles are competitively priced because lenders often want to recover the loan balance and move the vehicle efficiently. Prices vary by condition, mileage, location, and demand.

Can I finance a repo vehicle?

In many cases, banks and credit unions may offer financing options on repossessed vehicles they are selling. Buyers should contact the selling lender for details.

Explore More Repo Vehicle Options

Bank Car Auctions

Are Bank Car Auctions Legit?

Are Bank Car Auctions Legit? A Safe Buyer’s Guide to Bank Repossessed Cars

TL;DR

Yes, real bank car auctions are legitimate. Banks sell repossessed vehicles to recover unpaid loans, not to make retail profit. Most bank repos have clean titles and sell below dealer prices. The risk comes from fake auction sites and dealer middlemen pretending to be banks. If you verify ownership, title status, and VIN, buying a car directly from a bank can be one of the safest and cheapest ways to buy a used vehicle.


If you’ve searched for cheap cars online, you’ve probably seen the phrase “bank car auctions.”
And if you’re like most people, your next thought was:

“Is this legit, or is this another scam?”

That’s a fair question.

The used car world is full of confusing terms, misleading listings, and websites that look official but are not.
So let’s slow this down and explain how bank car auctions actually work, what’s real, what’s not, and how regular people buy repossessed cars directly from banks without getting burned.


What Is a Bank Car Auction?

A bank car auction is when a bank or credit union sells a vehicle it repossessed after a loan default.

Banks are not car dealers.
They do not want inventory.
They want their money back.

Instead of fixing the car up and reselling it like a dealer would, banks usually sell repossessed vehicles as is, often at wholesale level pricing.

That is where the opportunity comes from.


Are Bank Car Auctions Legit?

Yes. Real bank car auctions are legitimate.

Here is the important part.

Not every website that claims to sell bank repos is actually connected to a bank.

That distinction matters.


Why People Think Bank Auctions Are Sketchy

Most horror stories come from one of these situations:

• Fake “auction” websites charging access fees
• Salvage or insurance auctions mislabeled as bank repos
• Dealer middlemen pretending to be banks
• Cars with hidden title problems

When people say bank auctions are risky, they are usually talking about the wrong kind of auction.


Bank Repos vs Dealer and Salvage Auctions

Here is a simple breakdown.

Bank Repossessed Cars

• Owned by banks or credit unions
• Usually have clean titles
• Regular used vehicles
• Not insurance write offs
• Sold to recover loan balances

Salvage or Insurance Auctions

• Totaled or heavily damaged vehicles
• Salvage or rebuilt titles
• Often flood, collision, or theft losses
• Higher risk
• Not bank owned

If a listing does not clearly say who owns the vehicle, that is a red flag.


Do Bank Repo Cars Have Clean Titles?

Most do.

Banks financed these vehicles originally.
That means the car was road legal when the loan started.

Repossession does not damage a title.

There are exceptions:

• Abandoned vehicles
• Rare legal complications
• Extreme neglect

That is why buyers should always:

• Ask about the title
• Run a VIN report
• Confirm ownership before buying


Can Anyone Buy From a Bank Car Auction?

Yes. In many cases, anyone can buy.

You usually do not need:

• A dealer license
• Auction credentials
• Special access

Some banks sell directly.
Others list vehicles online.
Some work through local branches.

The challenge is finding them.

Banks do not advertise repossessed cars aggressively.
They do not optimize listings for search engines.
And they do not want tire kickers.


Why Banks Sell Repossessed Cars Cheap

Banks are not trying to maximize profit.

They want to:

• Close the loan
• Remove liability
• Clear the asset from their books

Holding vehicles costs money.
Every extra week hurts them.

That is why bank repos often sell below dealer pricing, even when the car runs and drives.


How to Tell If a Bank Car Auction Is Legit

Use this checklist:

• The seller is clearly identified as a bank or credit union
• No membership or access fees
• VIN is provided
• Title status is disclosed
• No pressure tactics
• No vague phrases like “bank style pricing”

If ownership details are hidden, walk away.


Step by Step: How to Buy a Car Directly From a Bank

  1. Find the listing
    Look for repossessed vehicles owned by banks or credit unions, not dealers pretending to be banks.

  2. Research the vehicle
    Run a VIN check.
    Compare market value.
    Look for obvious red flags.

  3. Ask smart questions
    Title status
    Location
    Payment method
    Inspection options

  4. Inspect if possible
    Some banks allow inspections.
    Some do not.
    Factor this into your offer.

  5. Make an offer or bid
    Many bank sales are simple best offer transactions, not bidding wars.

  6. Pay and transfer title
    Banks move slower but follow formal processes.
    Expect paperwork, not surprises.


Common Myths About Bank Car Auctions

1- Myth: Only dealers get the good cars
1- Truth: Dealers just know where to look

2-Myth: All bank repos are trashed
2-Truth: Many were repossessed due to missed payments, not abuse

3-Myth: You will get scammed
3-Truth: Scams happen when ownership is not verified


Why Buying Direct Beats Buying From Dealers

Dealers:
• Add markup
• Add fees
• Recondition cheaply
• Control the narrative

Banks:
• Sell as is
• Disclose ownership
• Do not upsell
• Do not play games

Different incentives lead to different outcomes.


FAQs

Are bank car auctions safe?
Yes, when the vehicle is truly bank owned and the title is verified.

Are bank repos cheaper than dealers?
Often yes, because banks are not selling for retail profit.

Do bank repos have clean titles?
Most do, since they were financed as standard vehicles.

Can I buy a bank repo online?
Yes. Many banks now sell repossessed vehicles digitally.


Final Takeaway

Bank car auctions are not shady.
Shady websites are.

When you understand how repos work, who owns the vehicle, and how banks operate, buying a repossessed car can be one of the smartest ways to avoid dealer games and overpaying.

Access matters more than luck.

find repo cars at the bank in the parking lot

Where to Find Repo Cars

Where to Find Repo Cars (7 Places Banks Sell Repossessed Vehicles)

In this guide you will learn where to find repo cars and how banks sell them.

If you are trying to find a cheap used car, you may have heard about repossessed vehicles.

These are cars, trucks, RVs, or boats that a bank takes back when the borrower stops making payments.

Most people assume repos only show up at auctions.

That is not always true.

In many cases, banks try to sell repos before they ever reach a public auction. That is where some of the best deals can be found.

The problem is simple.

Most banks do not advertise their repossessed vehicles very well. Many buyers never even know these listings exist.

One of the easiest ways to start is by using the free RepoFinder Repo Search tool to search current bank and credit union repos by state, vehicle type, keyword, make, model, and price.

If you want a car-focused starting point, you can also browse repo cars for sale directly from banks and credit unions instead of relying on auctions alone.

You can also explore RepoFinder’s list of bank repossessed cars to find lender-direct repo cars from banks, credit unions, and other financial institutions across the United States.


What Is a Repo Car?

A repo car is a vehicle that has been repossessed by a lender.

This usually happens when the owner stops making loan payments.

The bank or credit union takes the vehicle back and sells it to recover the remaining loan balance.

Banks are not car dealers.

They usually want to sell repossessed vehicles quickly and without hassle. Because of that, repo cars are often priced lower than similar vehicles on dealer lots.


Why Repo Cars Can Be Cheaper

Banks are not trying to make a profit selling repos.

They are simply trying to recover the money that was loaned.

Holding repossessed vehicles costs banks money. They must pay for storage, paperwork, and sometimes transport.

Because of this, banks often price repos to sell quickly.

That is why many buyers search for bank repo cars instead of dealership inventory.


7 Places to Find Repo Cars

Here are the most common places repossessed vehicles are sold.


1. Banks and Credit Unions

Many banks sell repossessed vehicles directly to the public.

Some keep a small list of repos on their website.

Others sell repos locally through word of mouth, sealed bids, internal listings, or auction partners.

This is where RepoFinder.com comes in.

RepoFinder helps buyers find banks and credit unions that are selling repossessed vehicles. Instead of searching dozens of individual lender websites, buyers can start with the free RepoFinder Repo Search tool and search current lender repos by state, vehicle type, keyword, make, model, and price.

From there, buyers can identify available listings and connect with the financial institution selling the vehicle.

This can help buyers find vehicles before they reach auctions or dealership lots, which may mean less competition and fewer middleman markups.


2. Repo Auctions

Auctions are the most well-known place to buy repossessed vehicles.

Banks often send unsold repos to auctions where dealers and the public can bid on them.

Some popular auction options include:

  • Auto auctions
  • Dealer auctions
  • Online auction platforms

The downside is competition.

Many dealers buy inventory from these auctions, which can drive prices higher. Auction buyers may also face bidding rules, buyer fees, transportation costs, and as-is vehicle conditions.


3. Police and Government Auctions

Police departments and government agencies also sell vehicles through auctions.

These may include:

  • Seized vehicles
  • Abandoned vehicles
  • Repossessed property

Some deals can be found, but inventory changes quickly and listings are often scattered across multiple websites.


4. Car Dealerships

Many used car dealerships actually buy their vehicles from repo auctions.

That means some cars on dealer lots started as repossessed vehicles.

The downside is markup.

Dealers must add profit margins, reconditioning costs, and overhead.

That is why buying repos closer to the source can sometimes lead to better deals.


5. Online Marketplaces

Some repos appear on general car marketplaces and classified sites.

These are usually listed by banks, dealerships, or auction resellers.

However, these listings are mixed with millions of regular used cars.

It can be difficult to tell which vehicles are actually repos.


6. Credit Union Listings

Credit unions are one of the most overlooked sources for repo vehicles.

Many credit unions repossess cars and sell them locally to recover their loan balances.

These listings are often posted on small web pages that can be difficult to find through normal searches.

This is another reason buyers use RepoFinder to locate lender repo sources and current repossessed vehicle listings.


7. Specialized Repo Listing Websites

Some websites specialize in tracking repossessed vehicles from banks and lenders.

These platforms gather lender sources and current listings in one place, making it easier for buyers to find vehicles that may otherwise be difficult to locate.

One of the most well-known examples is RepoFinder.com, which focuses on connecting buyers with repossessed vehicles owned by banks and credit unions.

Buyers can use the RepoFinder Repo Search page as a free starting point to search current lender repos by state, vehicle type, keyword, make, model, and price.

This helps buyers locate lender-direct repos that may never appear on a dealer lot or major public auction platform.


Final Thoughts

Repo cars can be one of the best ways to find affordable vehicles.

The key is knowing where to look.

Many buyers only search dealer lots or auction sites.

But banks and credit unions sell repossessed vehicles every day, sometimes before they ever reach those places.

That is why platforms like RepoFinder.com help buyers connect with financial institutions that are selling repos.

To begin, use the free RepoFinder Repo Search tool to search current bank and credit union repos nationwide by state, vehicle type, make, model, keyword, and price.

With a little research and patience, repo vehicles can offer excellent value for buyers looking for their next car, truck, SUV, RV, boat, motorcycle, or other lender-owned asset.

a repo car for sale at a credit union

What a Repo Car Really Is

What a Repo Car Really Is (And Why Most “Repo Car” Websites Get It Wrong)

If you search online for a repo car, you’ll see a lot of results.

Auctions.
Salvage cars.
Dealer listings.
“Bank repos” with fees stacked on top.

Here’s the problem:

👉 Most of those aren’t really repo cars anymore.

The word repo gets used loosely online.
Sometimes intentionally.
Sometimes out of confusion.

This article clears that up.

We’ll explain:

  • what a repo car actually is,

  • what it is not,

  • and how to tell the difference before you waste time or money.

No sales pitch.
Just the truth.


What Is a Repo Car? (Plain English)

A repo car is a vehicle that was:

  1. Financed by a bank or credit union

  2. Repossessed after the loan went into default

  3. Still owned by that financial institution

  4. Sold to recover the remaining loan balance

That’s it.

A real repo car is:

  • lender-owned

  • usually clean title

  • priced to liquidate, not maximize profit

Banks are not car dealers.
They don’t want inventory.
They want the loan off their books.

That incentive matters.


Why “Repo Car” Gets Misused Online

The term repo car attracts buyers.

People assume:

  • lower prices

  • cleaner titles

  • fewer games

So a lot of websites use the word even when the vehicle no longer fits the definition.

Let’s look at the most common mix-ups.


Mistake #1: Auction Cars Labeled as Repo Cars

Many vehicles start as repos.

But once a bank sends a vehicle to an auction, it stops being a repo car in the practical sense.

At that point:

  • ownership has changed hands or is in transition

  • auction incentives replace bank incentives

  • fees enter the picture

Large platforms like Copart or brokers like AutoBidMaster sell massive volumes of vehicles.

Some originated as repos.

But buyers are no longer dealing with the lender.

They’re dealing with:

  • auctions

  • brokers

  • bidding systems

  • buyer premiums

That’s a very different transaction.


Mistake #2: Salvage and Insurance Cars Called “Repos”

This one causes the most confusion.

Insurance total-loss vehicles are not repo cars.

They are:

  • accident vehicles

  • flood vehicles

  • hail vehicles

  • theft recoveries

These often carry:

  • salvage titles

  • rebuilt titles

  • or title branding

They can be fine for rebuilders.

But they are not repossessed loan collateral.

Using the word repo here is usually SEO, not accuracy.


Mistake #3: Dealer Cars Marketed as “Bank Repos”

Another common tactic.

A dealer buys a vehicle at auction.
Then relists it as a “bank repo.”

Technically, it once was.

But now:

  • the dealer owns it

  • markup has been added

  • profit is the goal

The bank is gone from the deal.

That distinction matters.


How Real Repossessed Cars Are Actually Sold

When a bank or credit union sells a repo directly, the process looks different.

Usually:

  • no bidding war

  • no buyer premium

  • no middleman fees

You contact the lender.
>You negotiate.
>You inspect.
>You buy.

It’s slower.
Less flashy.
But far more transparent.

And the pricing reflects liquidation, not speculation.


Why True Repo Cars Are Hard to Find Online

This is the core issue.

Banks:

  • don’t market well

  • don’t optimize SEO

  • don’t centralize listings

Each institution handles repos differently.

Some post on their own website.
>Some use PDFs.
>Some rely on internal lists.

There is no single national system.

That’s why buyers end up on auctions instead.

Not because auctions are better — but because they’re louder.


How to Tell If a Website Is Selling Real Repossessed Cars

Use this checklist.

If you answer no to more than one, it’s probably not a true repo sale.

Ask these questions:

  • Do you contact a bank or credit union directly?

  • Is there no bidding involved?

  • Are there no buyer premiums or auction fees?

  • Does the lender still hold the title?

  • Is the vehicle priced to sell, not to extract maximum profit?

Real repo cars feel boring.

That’s a good sign.


Why Title Status Matters

Most bank repos have clean titles.

Why?

Because:

  • they were everyday loan vehicles

  • insured and registered normally

  • repossession doesn’t damage a title

Salvage happens after loss events.

Repos happen after payment defaults.

Different problems.
Different risks.


So Where Should You Look for a Repossessed Car?

If you want:

  • real repos

  • lender-direct pricing

  • fewer games

You need to start at the source.

That means banks and credit unions.

The challenge is finding them all.

That’s where directories exist — not to sell cars, but to point buyers to the lenders themselves.

No auctions.
>No inventory flipping.
>No commissions.

Just access.


The Bottom Line

A repo car is not:

A real repo car is:

Once you understand that distinction, the noise disappears.

And buying gets simpler.


TL;DR

  • “Repo car” is widely misused online

  • Auctions and salvage cars dominate search results

  • True repossessed cars are sold directly by lenders

  • Clean titles and liquidation pricing matter

  • Knowing the difference saves money and time

repo car sold cheaper directly by a credit union

Are Repo Cars Cheaper? A Clear, Expert Answer

If you’ve ever wondered whether repo cars are actually cheaper than buying from a dealer, the short answer is yes — and usually by a wide margin.

As the team behind RepoFinder since 2009, we’ve seen tens of thousands of pure bank and credit-union repos move across the market. And after decades of tracking pricing, buyer behavior, and bank liquidation patterns, we can say with confidence:

True repos sold directly by banks are consistently cheaper than dealer retail, auction listings, or anything advertised as a “repo” by salvage sites.

Below is a fast, skimmable expert breakdown based on our firsthand experience.


Why Repo Cars Are Cheaper

1. Banks aren’t dealers — they don’t need profit margins

Banks don’t sell cars for a living.
When they repossess a vehicle, it becomes a hot potato on their books. Every day it sits, they lose money.

This is why:

  • Banks expect to sell below book value

  • They avoid commissions and fees

  • They prefer fast, clean liquidation over squeezing for every dollar

In contrast, auctions and dealers depend on markups and fees to survive.


2. Banks get more selling directly than dumping cars at auction

If a bank sends a car to auction, they may recover only 25–30% of its real value.
When they sell it themselves:

  • No auction fees

  • No commissions

  • No dealer cuts

They keep more — and you pay less.

This is why direct bank sales, the pure repos we list on RepoFinder, are some of the best values in the used-car market. You can browse current repo cars for sale or start with our directory of banks that sell repo cars.


3. True repos keep their clean titles

Almost all true bank repos we see:

  • Are under 6–7 years old

  • Have clean titles

  • Often still have factory warranty coverage

  • Are repossessed only for financial reasons, not damage

Banks cherry-pick the clean, desirable cars to sell themselves.
If a vehicle is severely damaged, many banks do send it to a salvage auction instead.

That’s why RepoFinder buyers overwhelmingly get clean-title cars. If you want a deeper breakdown, see do repo cars have clean titles.


The Biggest Misconception: “Repo” vs. Salvage Auctions

Many shoppers think “repo” means damaged or abused.
This misconception comes from salvage auction companies who hijacked the keyword.

When you Google “repo cars,” here’s what you usually get:

  • Salvage auction sites

  • Insurance write-offs

  • Dealer-only auctions

  • Total loss vehicles

  • Cars branded clean… until registration

These are not the pure repos banks sell.

We’ve seen countless Reddit posts where buyers thought they scored a cheap “repo” at an auction — only to discover the title branded after they registered it.

That never happens with true bank repos.


Real-World Price Example (We Watched This Happen)

One of the biggest deals we’ve tracked was a late-model Mercedes gull-wing sports car:

  • Original MSRP: $130,000+

  • Bank’s asking price after it sat awhile: $60,000

  • Low miles, clean title, great condition

It sold for less than half its real retail value simply because:

  • It was a niche car

  • Fewer eligible buyers

  • The bank didn’t want to sit on it

  • The longer it sits, the more they lose

We see price drops like this weekly — especially on specialty vehicles, boats, and higher-end models.


What Types of Repo Cars Are Cheapest?

Based on 16 years of tracking pure bank repos:

  • Common cars & trucks → reliably discounted

  • Older, low-mile vehicles → sometimes under $1,000

  • High-end luxury cars → massive discounts when they sit

  • Boats, ATVs, RVs → deep cuts when seasonal demand is low

  • Rare/specialty vehicles → biggest drops due to limited buyer pools

Buyers patient enough to watch listings for a few weeks often snag incredible deals. If price is your top priority, start with cheap repo cars and compare local inventory too.


Do Banks Negotiate? Almost Always.

In nearly every repo transaction we’ve observed:

  • Banks negotiate price

  • Banks negotiate financing

  • Banks negotiate interest rates

We’ve even seen banks drop interest rates to 1% on repo purchases because, in their eyes, selling the car is doing them a favor.

And yes — every bank we’ve ever seen allows inspections, including test drives, mechanic checks, and on-site evaluation.

Not one bank in 16 years has ever refused.


The #1 Mistake Buyers Make

Believing that all “repo” cars online are equal.

If it’s not:

  • Sold by a bank

  • Listed on a bank’s site

  • Stored at a bank

  • Priced by a bank

…then someone else already took the profit out of the deal.

Dealers, wholesalers, and salvage auctions use the word “repo” as bait
— even when the car is actually a salvage title, insurance loss, or dealer-purchase.

True repos come only from banks and credit unions. That’s why buyers should begin with real banks that sell repo cars, not recycled auction inventory.


Who Gets the Best Value With Repo Cars?

From our experience, repo buyers tend to fall into these groups:

  • Families watching every dollar

  • First-time car buyers

  • Bargain hunters

  • Tradespeople who value reliability

  • Flippers and small dealers

  • Anyone willing to be flexible on color/trim

Many car dealers use RepoFinder to build inventory — because they know exactly where the real deals are.


Why Repo Cars Are Cheaper — One Sentence

Repo cars are cheaper because you’re buying them directly from a bank that has no interest in holding or profiting from vehicles.


So… Are Repo Cars Cheaper? Absolutely. And Here’s Where to Start.

For buyers willing to step slightly outside the dealership system, repo cars offer:

  • Better pricing

  • Cleaner titles

  • Newer inventory

  • Less pressure

  • Transparent inspections

  • Optional bank financing

  • No commissions or dealer markups

And because we’ve been doing this since 2009, we’ve made RepoFinder the easiest way to find pure, direct-from-bank repos without the salvage auction noise.


Looking for a True Repo – Not a Salvage Auction?

If you want to browse real repos from banks and credit unions — the kind that stay under book value and keep clean titles — you can start right here with us at RepoFinder.

We link you directly to the banks. No middlemen. No commissions. Just real repos.

Start here: repo cars for sale, repo cars near you, or banks that sell repo cars.

clean title repo for sale at a bank instead of an insurance loss car auction

Bank Repos vs. Insurance-Loss Cars

Not All Repos Are the Same: Bank Repos vs. Insurance-Loss Cars

Many car buyers shop for repos to find deals. But most shoppers do not know something important. Not all repos are the same.
Some repos are clean-title vehicles taken by a bank because of missed payments.
Others are insurance-loss vehicles with hidden accident or flood history.
They may also be repossessed, but they are nothing like true bank repos.

This guide explains the difference in simple terms. It also explains why RepoFinder only links to true bank repos, not mixed salvage inventory.


Why People Shop for Repos in the First Place

Most shoppers want:

  • Lower prices

  • Honest listings

  • Clean titles

  • Normal wear

  • Easy buying steps

Bank repos often check all these boxes. But salvage auctions may not. They blend many types of cars together. This creates confusion for buyers.


Understanding True Bank Repos

A true bank repo is simple to understand.
The borrower stops paying.
The bank takes the vehicle back.
The vehicle is then sold.

Key traits of true bank repos

  • Clean titles in most cases

  • Normal wear from daily use

  • No insurance payout history

  • No flood branding

  • No structural rebuild

  • Owned by a bank or credit union

  • Often well maintained

  • Usually cheaper than dealer lots

Banks want the loss off their books quickly. That creates buyer value.


What Insurance-Loss “Repos” Actually Are

Insurance-loss cars are different.
They enter auctions after major events like:

  • Accidents

  • Floods

  • Total loss claims

  • Engine failures

  • Fire damage

  • Theft recovery

Sometimes the owner stops paying after the damage.
The lender repossesses what is left.
It still enters the system as a “repo,” but in truth it is a damaged insurance-loss unit.

Key traits of insurance-loss repos

  • May show a clean title now

  • Often become branded after registration

  • Often repaired by unknown shops

  • May include flood cars

  • May include structural damage

  • Often have hidden mechanical issues

  • Often sold “as-is” with no return

  • Often mixed with salvage auction inventory

These cars are nothing like pure bank repos.


Why Some Damaged Cars Still Show “Clean Title”

Many shoppers get confused here.
The title stays clean in some states until the car is:

  • Sold again

  • Registered in a new state

  • Returned to the DMV system

Then the system updates the title.
This is when buyers get shocked.

Example scenario

A car was totaled for flood damage.
It moves across state lines.
It arrives at an auction with a “clean title.”
A buyer wins the auction.
They try to register it.
Suddenly the title becomes branded.

This feels like a bait-and-switch.
It happens more than people know.


Why Insurance-Loss Repos Are Risky

Insurance-loss repos may look cheap, but the risk is high.
Buyers may face:

  • Huge repair bills

  • Engine issues

  • Electrical failures

  • Mold from flood damage

  • Frame rust

  • Safety problems

  • Poor rebuild work

  • Lower resale value

  • Difficulty getting full insurance

Many buyers think they found a deal.
Instead, they bought someone else’s headache.


Why True Bank Repos Are Safer

True bank repos come from payment issues, not damage issues.
This creates safer buying conditions.

Safer traits of true bank repos

  • No insurance total loss

  • No flood branding

  • No hidden rebuild

  • Fewer surprises

  • More transparent histories

  • Fair market prices

  • Motivated sellers

  • Cleaner VIN data

Banks also store and secure vehicles once recovered.
This preserves condition better than salvage lots.


A Simple Way to Remember the Difference

Here is the clearest way to understand it:

Bank Repo = Missed Payments

The vehicle was fine. The finances were not.

Insurance-Loss Repo = Damage

The vehicle had a major event.
The finances collapsed later.

Only one of these is safe for most shoppers.
The difference is huge.


Why Buyers Get Confused Online

Online marketplaces blend many inventory types.
Buyers see the word “repo” everywhere.
But in many listings, the term does not mean what people think.

Common shopper questions

“If it says clean title, is it clean?”
Not always. Some states delay the branding.

“Why does a repo have flood damage?”
Because it was a flood car before the repo.

“Can a wrecked car still be repossessed?”
Yes. Owners often stop paying after the damage.

“Can salvage auctions sell repos?”
Yes. But the repos there may be insurance losses.

These questions confuse many shoppers.
That is why the distinction matters.


How RepoFinder Cuts Through the Confusion

RepoFinder links directly to banks and credit unions.
>There are no salvage auctions mixed in.
>There are no insurance total-loss cars blended in.
>There are no wholesalers hiding damage.

RepoFinder focuses on:

  • True financial repos

  • Clean titles

  • Bank-owned inventory only

  • Direct listings with no middlemen

  • Clear VIN histories

  • Safer vehicles

  • More trustworthy deals

Shoppers use RepoFinder when they want real repos, not salvage leftovers.


What Buyers Can Expect at Banks and Credit Unions

Banks and credit unions usually offer:

  • Fair pricing

  • Real photos

  • Real descriptions

  • No dealer pressure

  • Simple selling terms

  • Transparent paperwork

Most banks want the vehicle sold quickly.
This avoids storing costs.
It also reduces financial risk.
These motives benefit the buyer.


What Buyers Can Expect at Salvage Auctions

Salvage auctions offer a different experience:

  • Damaged vehicles

  • Mixed inventory

  • Strict “as-is” policies

  • Major competition from professional dealers

  • Risky title status

  • Unknown repair quality

  • No test drives

  • High fees to bid and when you buy

Some buyers enjoy the challenge.
But most buyers want a safer option.
That safer option is usually the bank repo.


Questions Car Shoppers Commonly Ask

“How can I tell if a repo is a true bank repo?”

Check the seller.
If it is a bank or credit union, it is a true bank repo.
RepoFinder makes this easy because every listing is direct.

“Are bank repos always clean title?”

Most are clean, but check the VIN to be sure.
Banks rarely sell salvage units, but it can happen.

“Why do some repos look too cheap?”

Banks want quick sales.
They do not follow dealer pricing models.

“Can I inspect a bank repo?”

Yes. Most banks allow viewing.
Some allow third-party inspections.

“Do bank repos come with warranties?”

Usually no.
But they start with cleaner histories than salvage units.

“Why not just buy at Copart or IAA?”

Those sites include many damaged vehicles.
They also mix insurance loss repos with regular insurance losses. They all end up with a branded title in the end.
Shoppers do not always know which is which until it’s too late.

“Why is RepoFinder safer?”

It filters out salvage auctions entirely.
You only get links to real banks and credit unions.

Feature True Bank Repo Insurance-Loss Repo
Reason taken Missed payments Accident, flood, fire, theft, or major failure
Title status Usually clean Often becomes branded later
Hidden damage Low High
Insurance history Usually clean Often totaled
Buyer risk Low High
Best for Normal shoppers Professional rebuilders
Where found Banks & credit unions Salvage auctions

Final Thoughts

Most shoppers want safe and affordable cars.
True bank repos offer that path.
Insurance-loss repos offer cheap prices but high risk.
The difference is not small.
It affects title status, safety, and long-term value.

RepoFinder exists to remove the confusion.
It sends buyers directly to banks and credit unions.
>No salvage auctions.
>No insurance-loss traps.
>No title surprises.

If you want cleaner deals and clearer histories, true bank repos are the best choice.
And RepoFinder is the easiest way to find them.


repossessed used car for sale at a credit union

Why RepoFinder.com Should Be Your First Stop for Used Cars

Looking for a Used Car? Start Here

Buying a used car can feel confusing. Prices vary. Dealers use tricks. Auctions move too fast.

That’s where RepoFinder.com comes in. We help regular people find real repossessions for real savings.

You don’t need to be a dealer or go to a high energy auction where you’ll feel like a fish out of water. You just need to know where to look.

We’ll explain why RepoFinder.com is one of the best ways to find a used vehicle today.


What Is RepoFinder.com?

RepoFinder.com is a free website that helps you find repossessed vehicles, boats, RVs, and property.

We’re different from other car sites. We don’t sell cars or run auctions. We don’t charge and dealer fees because we’re not a dealer or an auction house.

Instead, we connect you directly to banks and credit unions who are selling their repossessed items.

These banks want to sell fast. That means you can often get a better deal.


Three Big Reasons to Use RepoFinder.com

Let’s break it down. Here are the top 3 reasons people trust RepoFinder.com when shopping for used cars.


1. Direct Access to Repos from Banks and Credit Unions

Most people don’t know this, but banks and credit unions often have vehicles they’ve repossessed from borrowers.

These repos are often:

  • Well-maintained

  • Sold at a discount

  • Ready for quick sale

Banks are not car dealers. They just want to get their money back. That’s good news for buyers like you.

At RepoFinder.com, you don’t buy from us. You buy straight from the bank.

This is different from:

  • Auction sites that require bidding

  • Dealers who mark up prices

  • Brokers who add middleman fees

Our site lists real links to each bank or credit union’s repo inventory. You go straight to the source.

You can call them. Visit them. Even make offers directly.

And yes—many banks even offer financing on their own repos. (You can read more about that here.)

This means you may get better loan terms than at a dealership.


2. A Central Map of Repos in All 50 States

RepoFinder.com is more than a search bar. It’s a map of the entire country’s repossessions.

Every state. Hundreds of banks and credit unions. All in one place.

You don’t have to search site after site. We’ve already gathered the links for you.

Just visit our state map. Click your state. You’ll see all local listings and banks with repos.

For example:

  • In Texas? You’ll see dozens of credit unions with repos.

  • In Florida? Many local banks list boats and cars weekly.

  • In California? You’ll find credit unions with clean-title SUVs and sedans.

You don’t need to know a bank’s name. You just click the state and browse.

It’s simple. It’s fast. And it’s always growing.


3. No Hidden Fees, Games, or Sign-Ups

Let’s be honest. Many car-buying sites are full of tricks.

They make you sign up. Perhaps they sell your info. Most likely they’ll push you toward high-priced dealers.

RepoFinder.com does none of that.

  • No dealer fees

  • No commissions

  • No middlemen

We’re not trying to sell you a car. We’re here to show you where the deals are at your local banks.

You just contact the seller (a bank) and make an offer. It’s that simple.

Many listings are “first come, first served.” That means you can move fast—and save big.


More Ways to Save with RepoFinder

Besides cars and trucks, you can also find:

  • Boats

  • RVs and campers

  • Motorcycles and ATV’s

  • Real estate

  • Equipment and machinery

Banks repossess more than cars. They sometimes list homes, jet skis, even tractors.

These items are usually listed on the bank’s own site. But we link you there.

That means you’re seeing true repo prices—not marked-up ones.


What Are the Risks?

Buying a repo does come with some things to watch out for. Here are a few:

  • Most repos are sold as-is

  • You may not get a warranty

  • Inspections are sometimes limited

But remember—this is the same deal the dealers get. They buy repos at low prices and resell them.

With RepoFinder, you get that same access, but you cut out the dealer markup.

If you’re smart and do a little research, you can save thousands.

We always suggest:

  • Running a vehicle history report

  • Asking if test drives are allowed

  • Getting a mechanic’s opinion if possible


How to Use RepoFinder in 3 Simple Steps

Step 1: Visit RepoFinder.com

Go to www.RepoFinder.com. It works on phones, tablets, and computers.

Step 2: Click Your State

Use the state map or the state list. Click where you live or want to shop.

Step 3: Browse the Repo Listings

Each bank or credit union has a link. Some take you to car listings. Some let you make offers online.

From there, you’re in control. You contact the seller. It’s you who asks about the vehicle… and it’s still you (and the bank) who work out your deal.


Who Is RepoFinder Best For?

RepoFinder is great for:

  • People who want to avoid dealers

  • Buyers looking to save money

  • Families who need a second vehicle

  • People who can wait for the right deal

If you need a car today, you might go to a dealer. But if you want a better deal, RepoFinder gives you a smarter option.


How Does RepoFinder Make Money?

That’s the best part—we don’t charge buyers anything.

Some banks pay a small fee to be listed. But most of the site is totally free.

Our goal is to help people find hidden deals. We believe in transparency and no gimmicks.

RepoFinder is supported by ads like most free websites on the internet. We also provide an enhanced service at RepoFinder Pro with no ads and other perks.


Tips to Get the Best Repo Deal

Here’s how to get the most out of RepoFinder:

  • Check weekly: Listings change fast

  • Be flexible: You may find better deals in nearby states

  • Ask about financing: Many banks offer it on their own repos

  • Move fast: Good deals don’t last long

  • Stay patient: Waiting for the right deal can pay off big


What Our Users Say

“I found my truck through a credit union linked on RepoFinder. Saved over $5,000 compared to dealer prices!” – Mike B., Colorado

“No auctions, no fees. I found a clean-title boat for under market value. Super easy.” – Janice R., Florida

“I used to flip cars. Now I just use RepoFinder to find my next ride.” – Paul L., Texas


Frequently Asked Questions (FAQ)

Do I need a dealer’s license?
No. Most repo listings are open to the public.

Are the vehicles clean title?
Most are, but check with the bank. Some may be rebuilt or salvage.

Can I test drive the car?
Sometimes, yes. It depends on the seller. Ask before making an offer.

Do I have to go to an auction?
Nope. RepoFinder shows you non-auction repos available to the public.

What if I live in a small state?
Browse nearby states too. Many banks sell to out-of-state buyers.


Final Thoughts: Why RepoFinder Works

RepoFinder.com is simple, free, and powerful.

We help people:

  • Find repossessions the public can actually buy

  • Connect directly to banks and credit unions

  • Avoid auctions, scams, and overpriced dealers

In a world full of tricks and hidden fees, we keep it easy.

If you’re buying a car, boat, RV, or even a home—start with RepoFinder.

You might be surprised what you find.


Ready to Start Your Search for used cars?

Browse repos by clicking your state on our Repo Map. It only takes a few seconds.

Just real listings.