Tag Archives: bank repo cars

bank repossessed cars with prices for sale at a credit union

Bank Repossessed Cars With Prices: How to Compare Listings and Total Cost

Ready to browse? Search current repo cars by state and price or view the nationwide list of bank repossessed cars.

TL;DR

  • Bank repo listings may show a set price, a minimum bid, or “taking bids.” These terms do not all mean the same thing.
  • Compare the exact year, trim, mileage, condition, and location before deciding whether a price is competitive.
  • Budget for costs beyond the vehicle price, such as taxes, title and registration, inspection, transportation, and repairs.
  • RepoFinder helps you search bank and credit union inventory by vehicle type, state, and price. The seller sets the price and sale terms.

If you’re searching for bank repossessed cars with prices, you want to see the numbers before you contact a lender. Some listings show a price. Others show a minimum bid or say “taking bids.”

That difference matters. A displayed amount may not be the final purchase price, and the listed price is only one part of your total cost. Here’s how to read repo car prices, compare listings, and build a realistic budget.

Examples of Price Information on RepoFinder

RepoFinder vehicle records can display different kinds of price information. These examples were checked on October 20, 2026. They illustrate the figures buyers may see; they do not guarantee that a vehicle is still available or that the lender will accept the displayed amount.

Vehicle record Location Price information shown
2020 Ford Escape Iowa $5,050 displayed in the vehicle record
2019 Hyundai Kona Iowa $6,250 displayed in the vehicle record
2014 Chevrolet Impala Utah Taking bids; $5,200 minimum bid and $5,500 NADA clean loan value

Inventory and lender terms can change. Confirm the vehicle’s availability, price, and sale process with the seller before traveling or making an offer.

What Do Repo Car Price Labels Mean?

A bank repossessed car listing may use one of several price terms. Read the listing carefully before deciding what you are willing to pay.

Asking price

An asking price is the amount the seller currently lists for the vehicle. It may be negotiable, or the seller may expect buyers to pay the posted amount. Ask the lender whether it is accepting offers.

Minimum bid

A minimum bid is the lowest amount the seller will consider through a bidding process. It is not necessarily the final price. Other buyers may bid more, and the seller’s rules determine how the bidding works.

“Taking bids”

“Taking bids” means the seller is inviting offers or bids instead of showing a fixed purchase price. Ask how to submit a bid, whether there is a deadline, and whether the lender has a minimum amount.

Book, loan, or estimated value

A book or loan value is an estimate. It is not automatically the seller’s asking price or the vehicle’s current market value. Use it as one reference point, then compare similar vehicles and account for condition and mileage.

How to Compare Bank Repo Cars for Sale

A low number can catch your attention, but the comparison is only useful when the vehicles are similar. Check:

  • Year, make, model, and trim: Different trims and options can have very different values.
  • Mileage: Compare vehicles with similar mileage.
  • Condition: Look for mechanical issues, body damage, missing parts, and needed repairs.
  • Location: A low price may be offset by the cost of inspecting or transporting the vehicle.
  • Title and history: Confirm the VIN, title status, and vehicle history with the seller.
  • Sale terms: Check whether the lender allows inspections, test drives, offers, or bidding.

For another pricing reference, compare the listing with current local vehicles and valuation tools. Our guide to Black Book car values explains how vehicle estimates work. You can also read our broader guide on whether repo cars are cheaper.

Calculate the Full Cost Before You Make an Offer

The listed price is not always the amount you will spend to buy and use the car. Build your budget around the full transaction:

Estimated total cost = purchase price or bid + taxes and registration + any seller fees + inspection and transportation + immediate repairs

The exact costs depend on the vehicle, your state, and the lender’s sale terms. Before committing, ask the seller:

  • Is the vehicle still available?
  • Is the displayed amount a firm price, minimum bid, or estimate?
  • Are there any additional lender or sale-platform fees?
  • Can I inspect the vehicle before making an offer?
  • What payment methods are accepted?
  • When and where must I pick up the vehicle?

Our buyer’s checklist for repo vehicles can help you review the vehicle, documents, pickup rules, and repair needs.

How to Find Bank Repossessed Cars With Prices

You can search RepoFinder’s nationwide inventory by vehicle type, state, and price:

  1. Open Repo Search.
  2. Choose cars and select a state, or search nationwide.
  3. Set your price range and compare the available listings.
  4. Open a listing to review its price information and seller details.
  5. Confirm availability and sale terms directly with the lender or seller.

You can also browse repo cars for sale or review banks that sell repo cars.

RepoFinder helps buyers locate bank and credit union inventory. The lender or seller controls the final price, bid process, and sale terms. For a step-by-step overview, read our guide on how to buy a repossessed car.

Frequently Asked Questions

Do banks list repossessed cars with prices?

Some listings show a price. Others show a minimum bid, an estimated value, or “taking bids.” Check the individual listing and confirm the current terms with the seller.

Does a minimum bid mean I can buy the car for that amount?

Not necessarily. A minimum bid is the starting amount the seller will consider. The final price depends on the sale process and the lender’s terms.

Are bank repossessed cars always cheaper?

No. A repo car may be priced competitively, but its condition, mileage, location, and sale terms affect its value. Compare similar vehicles and calculate the full cost before deciding.

What costs should I add to the listed price?

Include taxes, title and registration, inspection, transportation, repairs, and any fees stated in the seller’s terms.

Does RepoFinder set the price of a repo car?

No. RepoFinder helps buyers find lender inventory. The bank, credit union, or other seller sets the price and handles the sale.

Find Repo Cars That Fit Your Budget

A posted price is a useful starting point, but it does not tell you everything about a repo car. Compare similar vehicles, check the seller’s terms, and include the full cost in your budget before making an offer.

Search current bank and credit union repo cars by price or browse repo cars for sale.

You can buy a repo car without being a bank or credit union member.

Can You Buy Repo Cars Without Being a Member?

TL;DR: In many cases, you can buy a repossessed car without being a member of the bank or credit union selling it. Some lenders sell repo vehicles directly to the public, while others may require membership for financing or give members priority. Always contact the lender to confirm its rules, inspect the vehicle, verify the title, and understand all purchase costs before paying.

Yes, in many cases you can buy a repo car without being a member of the bank or credit union selling it.

Banks and credit unions repossess vehicles because a borrower stopped making payments on an auto loan. After taking possession of the vehicle, the financial institution typically wants to sell it and recover as much of its money as possible.

That means the lender’s primary goal is usually to complete a legal, straightforward sale. It may not require the buyer to already have an account or loan with the institution.

However, every bank and credit union sets its own rules. Some lenders sell repossessed vehicles to anyone, while others may give members priority, require membership for financing, or use different procedures for accepting offers.

If you are looking for current lender-owned vehicles, you can search RepoFinder’s nationwide repo listings by state, vehicle type, keyword, and price.

Do You Have to Be a Bank Member to Buy a Repo Car?

Usually, no.

Many banks sell repossessed cars, trucks, SUVs, RVs, boats, motorcycles, and other property to the general public. The buyer may not need an existing checking account, savings account, or auto loan with that bank.

Credit unions can be slightly different because they are membership-based financial institutions. A credit union may allow anyone to purchase one of its repossessed vehicles, but it may have separate membership requirements for financing or other services.

Before assuming that membership is required, contact the lender selling the vehicle and ask:

  • Is the repossessed vehicle available to nonmembers?
  • Does the buyer need to open an account?
  • Is membership required only for financing?
  • Are offers accepted from the public?
  • Does the lender use a fixed price, auction, or sealed-bid process?
  • What payment methods are accepted?
  • Is the vehicle sold as-is?

The answer can vary from one lender to another, so buyers should always verify the requirements directly.

You can also browse RepoFinder’s list of banks that sell repo cars to locate financial institutions offering repossessed vehicles.

Why Do Banks and Credit Unions Sell Repo Cars to the Public?

Banks and credit unions are lenders, not traditional car dealerships. They generally do not want to keep repossessed vehicles sitting in storage for months.

Selling the vehicle allows the lender to:

  • Recover money from the unpaid loan
  • Reduce storage and maintenance costs
  • Resolve the borrower’s outstanding account
  • Remove the vehicle from its inventory
  • Convert the repossessed asset into cash

Because the lender is trying to recover money rather than operate a dealership, the purchasing process may be different from buying a vehicle from a dealer.

The lender may list the vehicle at a set price, accept offers, conduct a local sale, or send the vehicle to an auction. When a bank or credit union sells directly to the public, buyers may be able to avoid some dealer markups and auction-related fees.

You can browse current repo cars for sale to see the types of lender-owned vehicles available.

Can Nonmembers Finance a Repo Car?

Possibly, but financing rules are often different from purchasing rules.

A bank or credit union may allow a nonmember to buy a repossessed vehicle with cash, a cashier’s check, or approved outside financing. However, the lender may require membership before offering its own auto loan.

Some credit unions allow a buyer to join before applying for financing. Others may require the buyer to meet geographic, employment, organizational, or other eligibility requirements.

Before making an offer, ask the lender:

  • Does the lender finance its own repossessed vehicles?
  • Can nonmembers apply for financing?
  • Is membership required before applying?
  • What credit requirements apply?
  • Is a down payment required?
  • Can the buyer use financing from another bank?
  • How quickly must payment be completed?

Buyers who need financing should get preapproved when possible. Having financing arranged ahead of time can make it easier to act quickly when a desirable repo vehicle becomes available.

For more information, see Buying and Financing a Repossessed Vehicle at a Bank.

Can You Buy a Repo Car From a Credit Union Without Joining?

Sometimes, yes.

Credit unions commonly sell repossessed vehicles to recover losses from unpaid loans. Some make those vehicles available to the public, even if the buyer is not already a member.

Other credit unions may have different requirements. For example, a credit union might:

  • Allow anyone to submit an offer
  • Require membership before completing the sale
  • Require membership only for financing
  • Give members an early opportunity to purchase
  • Sell the vehicle through a public auction
  • Require the buyer to meet specific eligibility rules

Membership is often easier to obtain than buyers expect, but buyers should not assume that joining is necessary. Contact the credit union and ask about its current repo-sale policy.

RepoFinder helps buyers locate bank-owned cars for sale and other repossessed vehicles offered by lenders throughout the United States.

How to Buy a Repo Car Without Being a Member

The process is usually straightforward.

1. Find a lender-owned repo vehicle

Start by searching current bank and credit union repos by location, vehicle type, make, model, and price.

RepoFinder includes listings for cars, trucks, SUVs, vans, RVs, boats, motorcycles, trailers, powersports, commercial vehicles, and equipment.

2. Review the listing carefully

Look for the vehicle identification number, mileage, asking price, location, photographs, sale deadline, and contact information.

Inventory can change quickly, so a vehicle may sell before the listing is removed.

3. Contact the selling bank or credit union

RepoFinder helps buyers locate the vehicle, but the selling lender controls the final sale.

Ask the lender to confirm:

  • The vehicle is still available
  • The current price
  • The title status
  • Whether there are liens or title issues
  • Whether an inspection is allowed
  • Whether a test drive is available
  • Whether nonmembers may purchase
  • What payment methods are accepted
  • Where the vehicle must be picked up

4. Inspect the vehicle

Most repossessed vehicles are sold as-is. If possible, inspect the vehicle in person or hire a qualified mechanic to examine it.

Check the tires, engine, transmission, warning lights, fluids, body, interior, brakes, electronics, and signs of water damage or neglect.

A repo vehicle is not automatically a salvage vehicle. Repossession generally relates to a loan default, while a salvage title usually relates to major damage or an insurance total loss. Even so, always verify the title and vehicle history before buying.

5. Check the market value

Compare the lender’s price with current values for similar vehicles. Consider mileage, trim level, condition, location, taxes, transportation, registration, repairs, and other purchase costs.

A low asking price does not necessarily mean the vehicle is a good deal if it needs major repairs.

6. Submit an offer or complete the purchase

Depending on the lender’s rules, you may submit an offer, participate in bidding, or pay the listed price.

Follow the lender’s instructions carefully. Ask for written confirmation of the purchase terms, payment deadline, pickup requirements, and documents you will receive.

What Documents Do You Need to Buy a Repo Car?

The requirements vary, but buyers may need:

  • Government-issued identification
  • Proof of insurance
  • Payment in an approved form
  • A signed bill of sale
  • Purchase agreement
  • Title or title-transfer documents
  • Registration paperwork
  • Financing documents, if applicable

Ask the lender which documents will be provided and whether the title is immediately available. If the title is delayed, find out why and how the transfer will be completed.

Are Repo Cars Cheaper When You Buy Directly From a Bank?

They can be, but there is no guaranteed discount.

Banks and credit unions may price repossessed vehicles competitively because they want to sell them quickly. Buying directly from a lender may also reduce dealer markups and certain auction-related expenses.

However, buyers still need to account for:

  • Repairs and maintenance
  • Taxes and registration
  • Transportation or shipping
  • Inspection fees
  • Insurance
  • Possible buyer or administrative fees
  • Financing costs

The best way to evaluate a repo is to compare its total cost with similar vehicles from dealerships and private sellers.

You can also compare local inventory by searching repo cars near you.

Are Bank Repo Cars Safe to Buy?

Many repossessed vehicles can be good purchases, but they should be evaluated like any other used vehicle.

A borrower’s financial problems do not automatically mean the vehicle was abused. Some repos are newer vehicles with ordinary wear and maintenance histories. Others may have been neglected, damaged, vandalized, or stored improperly.

Before purchasing, verify:

  • Vehicle history
  • Title status
  • Mileage
  • Mechanical condition
  • Accident history
  • Outstanding recalls
  • Whether keys are included
  • Whether the vehicle starts and drives
  • Whether personal property remains inside
  • Whether the lender provides any warranty

Never rely only on photographs or a low price.

Final Thoughts

You can often buy a repo car without being a member of the bank or credit union selling it. The key is understanding the lender’s specific rules.

Some financial institutions sell directly to the public. Others may require membership for financing, give members priority, or use a public auction process.

The safest approach is to find the vehicle, contact the selling lender, verify the purchase requirements, inspect the vehicle, confirm the title, and understand every cost before paying.

RepoFinder helps buyers search current repossessed cars and other lender-owned vehicles from banks and credit unions across the country. Start by using the RepoFinder search tool or browse the list of bank repossessed cars.

FAQ

Can I buy a repo car if I am not a bank customer?

Yes, many banks sell repossessed vehicles to the general public. However, each lender sets its own rules, so confirm the requirements before making an offer.

Do I have to join a credit union to buy its repo car?

Not always. Some credit unions allow nonmembers to purchase repossessed vehicles, while others may require membership for the purchase or financing.

Can I finance a repo car without being a member?

Possibly. You may be able to use outside financing, pay cash, or join the credit union before applying for its auto loan.

Are repo cars sold directly by banks?

Some are. Banks and credit unions may sell repos directly, list them through a third party, or send them to an auction.

Does RepoFinder sell the repo cars listed on its website?

No. RepoFinder helps buyers locate current bank and credit union repos. The selling lender controls the price, condition, title, payment terms, and final sale.

Do repo cars have clean titles?

Many lender-owned repos have clean titles, but repossession does not guarantee a clean title. Always verify the title status and vehicle history with the selling lender.

Where can I find repo cars for sale without joining a bank?

You can use RepoFinder to search current repos from banks, credit unions, and other financial institutions. Contact the lender directly to confirm whether nonmembers may purchase.

bank repo shopping

Why Most Repo Car Websites Aren’t Actually Showing You Bank Repos

Why Most Repo Car Websites Aren’t Actually Showing You Bank Repos

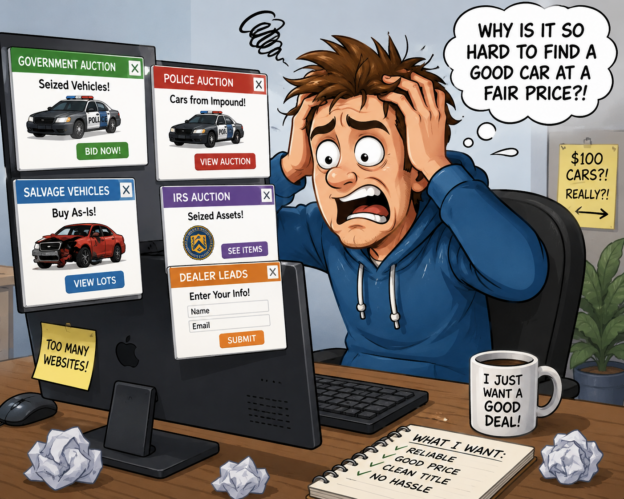
If you’ve searched online for repo cars, you’ve probably seen websites promising everything from $100 government vehicles to police seizures, IRS auctions, foreclosures, and repossessed cars all on the same page.

At first glance, it sounds exciting.

But here is the problem: many buyers think they are looking at real bank repos when they are actually being shown auction listings, salvage vehicles, government surplus property, dealer leads, or classified ads.

That difference matters.

Most buyers searching for repo cars are not trying to chase confusing auction hype. They want a real vehicle, a fair price, and a clear path to contact the seller.

They want real bank repos.

Understanding the difference can save you time, money, and frustration.

Want to skip auctions and browse repo cars directly from banks?

RepoFinder helps buyers search current bank and credit union repos, then buy directly from the selling lender.

Not All “Repo” Sites Are the Same

Many websites use the word “repo” as a catch-all term for auctions, seizures, surplus property, salvage vehicles, and classified listings.

That can be confusing for buyers.

Here is the simple difference:

Many Repo Websites Promote

  • Police auctions
  • Government seizures
  • IRS auctions
  • Salvage auctions
  • Dealer auctions
  • Classified listings
  • Lead-generation offers

RepoFinder Focuses On

  • Bank repos
  • Credit union repos
  • Current lender inventory
  • Direct lender contact information
  • No dealer markup
  • Nationwide repo listings
  • Searchable repo inventory

What Is a Real Bank Repo?

A bank repo is a vehicle that was financed by a bank, credit union, or other lender and later repossessed after the borrower stopped making payments.

Once the lender takes possession of the vehicle, it may choose to sell it directly to recover part of the loan balance.

These vehicles often include:

  • Cars
  • Trucks
  • SUVs
  • RVs
  • Motorcycles
  • Boats
  • Commercial vehicles

In many cases, the lender simply wants to recover its money and move the vehicle quickly.

That creates opportunities for buyers who know where to look.

Why Buyers Search for Bank Repos

People are attracted to bank repos because they often offer advantages over traditional used-car lots.

Potential benefits include:

  • Competitive pricing
  • No dealer markup
  • Direct access to the selling lender
  • Transparent ownership history
  • Many vehicles have clean titles
  • Financing may be available through the selling institution

While every vehicle should be inspected before purchase, bank repos have become popular because buyers are dealing directly with the financial institution rather than multiple middlemen.

That is why many shoppers use RepoFinder’s searchable repo inventory to look for current repos from banks, credit unions, and other financial institutions.

The Problem With Many Repo Websites

Many websites use the term “repo” very broadly.

A site may advertise repo vehicles while also promoting:

  • Police auctions
  • Government surplus sales
  • IRS seizures
  • DEA seizures
  • Salvage auctions
  • Dealer auctions
  • Classified listings
  • Foreclosures

These are not the same thing.

A police auction is not a bank repo.

A salvage auction is not a bank repo.

A government surplus vehicle is not a bank repo.

A classified ad is not a bank repo.

Combining all of these categories together can make it difficult for buyers who specifically want lender-direct inventory.

The $100 Repo Car Myth

One of the most common marketing claims online involves “$100 cars” or vehicles selling for pennies on the dollar.

Technically, some auctions may start bidding at very low amounts.

That does not mean desirable vehicles sell for those prices.

In reality, popular cars, trucks, and SUVs attract multiple bidders and often sell closer to market value.

Smart buyers focus on value rather than hype.

A vehicle priced fairly by a bank or credit union can be a much better purchase than chasing unrealistic auction claims.

Bank Repos vs Police Auctions: What’s the Difference?

Bank repos and police auctions can both offer used vehicles, but they are not the same source of inventory.

Bank repos are usually vehicles repossessed by a lender after loan default. Police auctions usually involve seized, abandoned, impounded, or surplus vehicles.

That difference can affect title status, condition, buying process, fees, financing, and who the buyer contacts.

Feature Bank Repos Police Auctions Salvage Auctions
Sold by banks or credit unions Often No No
Direct lender contact Yes No No
Financing may be available Often Rarely Rarely
Clean titles are common Often Varies Often no
Buyer fees Usually lower or none May apply Often apply
Final price Often listed upfront Determined by bidding Determined by bidding

Bank Repos vs Auction Vehicles

Let’s compare the buying experience more directly.

Bank Repos

  • Sold by banks and credit unions
  • Often available with lender contact information
  • Frequently include financing options
  • Commonly have clean titles
  • Pricing is usually straightforward

Auction Vehicles

  • Sold through bidding
  • Final price is unknown until auction ends
  • Buyer fees may apply
  • Salvage vehicles are common
  • Competition can drive prices higher

Neither approach is automatically better.

The key is understanding what you’re actually shopping for.

Why RepoFinder Takes a Different Approach

RepoFinder was built around a simple idea:

Help buyers find repossessed vehicles directly from banks and credit unions.

RepoFinder is not an auction company. RepoFinder helps buyers search current repossessed vehicles from banks, credit unions, and financial institutions nationwide. Buyers can then contact the selling lender directly.

Instead of focusing primarily on auctions, RepoFinder helps users search current repo inventory from financial institutions across the United States.

Buyers can search by vehicle type, state, make, and model while connecting directly with the lender selling the vehicle.

That means less time sorting through unrelated auctions and more time finding actual lender-owned inventory.

For example, buyers can search for repo cars for sale, browse repo trucks, or look for vehicles by state and make using RepoFinder’s search tools.

Search Current Bank and Credit Union Repos

Whether you’re looking for:

  • Repo cars
  • Repo trucks
  • Repo SUVs
  • Repo RVs
  • Repo boats
  • Repo motorcycles
  • Commercial equipment

RepoFinder helps connect buyers with current inventory from banks, credit unions, and other financial institutions nationwide.

The goal is simple:

Search current bank and credit union repos, then buy directly from the selling lender.

Ready to Search Real Bank Repos?

Browse current repossessed cars, trucks, SUVs, RVs, boats, motorcycles, and more from banks and credit unions nationwide.

Search Repo Inventory

Final Thoughts

Not all repo websites are built the same.

Many focus on auctions, government seizures, classified ads, or salvage inventory.

If your goal is to find actual bank-owned vehicles being sold by lenders, it’s important to understand the difference.

Before spending hours searching through auction listings, make sure you’re looking in the right place.

The more directly you can connect with the institution selling the vehicle, the easier it becomes to compare options and make an informed purchase.

That’s exactly what RepoFinder was designed to do.

Frequently Asked Questions

What is a bank repo vehicle?

A bank repo vehicle is a car, truck, SUV, RV, boat, motorcycle, or other asset repossessed by a lender after loan payments were not made.

Are bank repos the same as police auction vehicles?

No. Police auction vehicles usually come from law enforcement agencies, impound lots, or government sources. Bank repos are owned and sold by banks, credit unions, or financial institutions.

Are bank repos the same as salvage auction vehicles?

No. Salvage auctions often include damaged vehicles, insurance losses, and vehicles with salvage or rebuilt titles. Many bank repos are ordinary financed vehicles that were repossessed after loan default.

Does RepoFinder sell vehicles directly?

No. RepoFinder helps buyers search repossessed vehicles from banks, credit unions, and other lenders. Buyers contact the selling institution directly.

Are repo vehicles cheaper than dealer vehicles?

Many repo vehicles are competitively priced because lenders often want to recover the loan balance and move the vehicle efficiently. Prices vary by condition, mileage, location, and demand.

Can I finance a repo vehicle?

In many cases, banks and credit unions may offer financing options on repossessed vehicles they are selling. Buyers should contact the selling lender for details.

Explore More Repo Vehicle Options