Tag Archives: repo cars

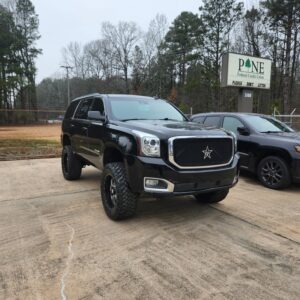
Real repo car sold by a credit union

What Makes a REAL Repo Car Different From a Regular Used Car?

Real repo car sold by a credit union

If you have searched online for repo cars lately, you have probably noticed something strange.

A lot of “repo car” websites are not really selling bank repos at all.

Many are filled with salvage vehicles, dealer inventory, or auction listings mixed together. That makes it hard to know what is actually a real repossession.

At RepoFinder, we focus on something different:

REAL repo cars from banks and credit unions.

That means vehicles that were repossessed by financial institutions and are now being sold directly to the public, often without dealer markups or middlemen.

What Is a Real Repo Car?

A repo car is a vehicle taken back by a lender after missed loan payments.

Banks and credit unions usually do not want to keep these vehicles. Their goal is simple:

Recover money quickly.

That creates opportunities for buyers looking for lower prices.

Unlike many used car dealers, banks are not trying to maximize profit on every vehicle. They mainly want to clear inventory and recover part of the loan balance.

That is why real bank repos can sometimes sell below normal market value.

Why Buyers Like Bank Repo Cars

Here are a few reasons repo vehicles continue to grow in popularity:

1. Lower Prices

Banks are not traditional car dealers.

Many simply want the vehicle sold fast.

That can lead to better pricing compared to dealer lots.

2. Cleaner Inventory

Many real repos are regular daily-driver vehicles:

  • Trucks
  • SUVs
  • Sedans
  • Vans
  • Motorcycles
  • RVs
  • Boats

In many cases, these are clean-title vehicles instead of heavily damaged salvage units.

3. Direct Buying

One of the biggest advantages is skipping extra layers.

With RepoFinder, buyers can often go directly to the bank or credit union listing page instead of bouncing through multiple auction companies or lead-generation sites.

That means:

  • No dealer pressure
  • No hidden middleman
  • No unnecessary markups

Watch Out for Fake “Repo” Listings

This is where many buyers get frustrated.

Some websites use the word “repo” for almost everything.

You may click expecting a bank-owned vehicle and end up seeing:

  • Salvage auctions
  • Insurance-totaled cars
  • Dealer inventory
  • Flood vehicles
  • Wholesale auction units

Those are not the same thing as direct bank repos.

A real repo site should clearly connect buyers to banks and credit unions that actually own the vehicles.

That is the difference.

Are Repo Cars Safe to Buy?

Usually, yes, but smart buyers still inspect everything carefully.

Just like any used vehicle, condition matters.

Some repos are excellent deals. Others may need work.

Before buying, always check:

Many banks allow inspections before purchase.

That is a major advantage over some fast-moving auctions.

Why RepoFinder Is Different

RepoFinder is built around one core idea:

Help buyers find actual bank and credit union repos nationwide.

Instead of pretending to be a giant dealership, RepoFinder works more like a nationwide repo directory.

You can browse by:

  • State
  • Vehicle type
  • Bank or credit union
  • Cars, trucks, SUVs, RVs, boats, and more

That makes it easier to find real repos near you without digging through junk listings.

Final Thoughts

The repo market is growing fast.

But so is confusion.

Many sites throw the word “repo” around loosely. That makes buyers think they are looking at direct bank repos when they are really viewing salvage auctions or dealer inventory.

Real repo cars are different.

They come directly from lenders. They are often priced aggressively. And they can offer serious value for smart buyers willing to do a little research.

If you want to skip the middleman and browse real bank repos nationwide, RepoFinder is a great place to start.

How to Find Bank Repo Cars for Sale Without Paying Dealer Fees

How to Find Bank Repo Cars for Sale Without Paying Dealer Fees

How to Find Bank Repo Cars for Sale Without Paying Dealer Fees

Buying a Used Car Does Not Have to Mean Paying Dealer Fees

Buying a used car can get expensive fast.

You find a vehicle online. The price looks fair. Then you visit the dealer and suddenly the real cost is higher than expected.

There may be document fees, dealer prep fees, add-ons, warranty pressure, financing products, and other charges that were not obvious at first.

That is one reason more shoppers are searching for bank repo cars for sale.

A bank repo car is a vehicle that was repossessed by a bank, credit union, or lender after the borrower stopped making payments. Once the lender takes the vehicle back, it usually wants to sell it and recover part of the unpaid loan balance.

For buyers, that can create a real opportunity.

Instead of shopping only through dealerships, you may be able to buy directly from the bank or credit union that owns the vehicle.

That is where RepoFinder.com can help.

RepoFinder helps shoppers find repossessed cars, trucks, SUVs, motorcycles, RVs, boats, aircraft, equipment, and real estate listed by banks and credit unions across the United States.

Why Banks Sell Repossessed Cars

Banks and credit unions are not car dealers.

They usually do not want to store vehicles, clean them, advertise them, or keep them sitting around for months.

When a lender repossesses a vehicle, the goal is usually simple.

They want to sell it.

That means many repo cars are priced to move. Some are sold by sealed bid. Some are listed with a set asking price. Others may be sold through a small local auction or directly through the lender’s website.

Every bank handles repos a little differently.

Some credit unions have a clean online list of repossessed vehicles. Others post a simple PDF. Some only show inventory when they have something available.

That is why repo shopping can be confusing if you do not know where to look.

Are Bank Repo Cars Cheaper Than Dealer Cars?

Bank repo cars can be cheaper than similar vehicles at dealerships, but not every repo is automatically a bargain.

The final price depends on the vehicle, condition, mileage, market demand, location, and the lender’s asking price.

The biggest advantage is not always just the price.

It is the buying path.

When you buy from a dealer, the dealer needs to make a profit. That often means markup, fees, add-ons, financing products, warranties, and other charges.

When you buy directly from a bank or credit union, you may avoid many of those dealership costs.

That does not mean you should skip your homework. You still need to compare prices, inspect the vehicle, check the title, and understand the sale terms.

But if you are patient, bank repos can be one of the best places to look for used vehicle deals.

How to Find Bank Repo Cars Near You

The hardest part of repo shopping is finding the lenders that actually have inventory.

You could search Google for hours using phrases like:

  • bank repo cars near me
  • credit union repossessed cars
  • bank owned vehicles for sale
  • repo cars for sale in Texas
  • repo trucks for sale near me

The problem is that many bank repo pages are hard to find. Some are buried deep on lender websites. Others disappear when inventory sells. Some are not optimized for search at all.

RepoFinder.com was built to solve that problem.

Instead of searching one bank at a time, you can use RepoFinder to find banks and credit unions that sell repossessed vehicles directly.

You can start with repo cars for sale, then explore nearby states or other vehicle types.

If you are looking for trucks, visit repo trucks for sale.

If you are looking for SUVs, visit repo SUVs for sale.

You can also browse banks that sell repo cars to find lenders directly.

Why Buying Directly From Banks Is Different

Buying a repo from a bank is not always like buying from a dealership.

A dealer usually has salespeople, financing offices, service departments, trade-in offers, extended warranty pitches, and retail markups.

A bank repo sale is often much simpler.

The bank may provide basic details such as year, make, model, mileage, VIN, photos, asking price, and contact instructions.

Some lenders may allow test drives or inspections. Others sell repos as-is.

That means the buyer has more responsibility.

You may get a better buying opportunity, but you also need to do more research before making an offer.

What to Check Before Buying a Repo Car

Before buying any repossessed vehicle, slow down and check the details.

A low price is only helpful if the vehicle is worth buying.

Check the Vehicle History

Use the VIN to research the vehicle history.

Look for accident history, title brands, odometer issues, flood damage, or prior salvage records.

Many repossessed vehicles may have clean titles, but you should still verify the title before buying.

Compare the Market Value

Compare the repo vehicle against similar listings in your area.

Look at mileage, trim level, condition, options, age, and location.

A repo is only a good deal if the price makes sense compared with the rest of the market.

Inspect the Mechanical Condition

Repos are commonly sold as-is.

That means the lender may not repair problems after the sale.

Have the vehicle inspected by a mechanic when possible. At minimum, check the tires, brakes, fluids, warning lights, battery condition, engine noise, transmission shifting, leaks, and signs of neglect.

Read the Sale Terms

Every bank has its own rules.

Credit unions often offer financing on their own repo vehicles, which can be a major advantage for buyers. Instead of paying cash upfront, qualified buyers may be able to finance the repo directly through the same credit union selling it. In most cases they will sell to the highest bidder, but some list a firm price.

Read the instructions carefully before contacting the lender.

Watch for Extra Costs

Even without dealer fees, there may still be taxes, title fees, registration costs, transport costs, inspection costs, or repair costs.

Build those into your budget before making an offer.

Can You Finance a Bank Repo Car?

Sometimes, yes.

Some banks and credit unions may offer financing on the repos they sell. Others may require outside financing or full payment.

This can be a hidden advantage.

If a credit union owns the vehicle, it may be open to financing the buyer, especially if the buyer qualifies.

That can make the process easier than paying cash.

But do not assume financing is available. Ask the lender directly.

Good questions to ask include:

  • Do you offer financing on this repo?
  • Is the vehicle sold as-is?
  • Is the title clean?
  • Are bids required?
  • Can I inspect the vehicle before making an offer?
  • Are there any extra fees?
  • When is payment due?
  • Do you have other repos available?

Why RepoFinder Is Different From Dealer Listing Sites

Most used car websites are built around dealers.

That means the listings usually come from dealerships, auctions, lead sellers, or retail inventory feeds.

RepoFinder is different.

RepoFinder focuses on helping shoppers find repossessed assets from banks and credit unions. The goal is to connect buyers with the source, not add another middleman.

That matters because lender-owned vehicles may not always appear on the big dealer sites.

Some are only listed on small bank pages, local credit union websites, or repo inventory pages that are easy to miss.

RepoFinder helps organize those opportunities in one place.

What Types of Repos Can You Find?

RepoFinder is not just for cars.

Depending on available inventory, shoppers can find many types of repossessed and bank-owned assets.

These may include:

  • Cars
  • Trucks
  • SUVs
  • Motorcycles
  • RVs
  • Boats
  • Aircraft
  • Commercial vehicles
  • Equipment
  • Real estate and REO property

Inventory changes often because repos sell and new ones appear.

That is why checking regularly can help.

Best Strategy for Finding a Good Repo Deal

The best repo shoppers are patient.

Do not expect every listing to be perfect.

Some vehicles will be too far away. Others will already be sold. Some will be priced too high. And some will need repairs.

The key is to keep watching.

Check your state page. Check nearby states. Look at banks and credit unions directly. Compare prices. Move quickly when a good listing appears.

Good repo deals do not always last long.

You can also search by location using repo cars near me to find more options.

Final Thoughts on Finding Bank Repo Cars

Bank repo cars can be a smart option for buyers who want to avoid dealership markups and shop closer to the source.

They are not risk-free. You still need to research the vehicle, inspect it, understand the sale terms, and compare prices.

But for shoppers willing to do a little homework, repossessed cars from banks and credit unions can be one of the most overlooked ways to find a used vehicle deal.

RepoFinder.com makes that search easier by helping you find banks and credit unions that sell repos directly.

Start with repo cars for sale or browse banks that sell repo cars to begin your search.
find repo cars at the bank in the parking lot

Where to Find Repo Cars

Where to Find Repo Cars (7 Places Banks Sell Repossessed Vehicles)

In this guide you will learn where to find repo cars and how banks sell them.

If you are trying to find a cheap used car, you may have heard about repossessed vehicles.

These are cars, trucks, RVs, or boats that a bank takes back when the borrower stops making payments.

Most people assume repos only show up at auctions.

That is not always true.

In many cases, banks try to sell repos before they ever reach a public auction. That is where some of the best deals can be found.

The problem is simple.

Most banks do not advertise their repossessed vehicles very well. Many buyers never even know these listings exist.

One of the easiest ways to start is by using the free RepoFinder Repo Search tool to search current bank and credit union repos by state, vehicle type, keyword, make, model, and price.

If you want a car-focused starting point, you can also browse repo cars for sale directly from banks and credit unions instead of relying on auctions alone.

You can also explore RepoFinder’s list of bank repossessed cars to find lender-direct repo cars from banks, credit unions, and other financial institutions across the United States.


What Is a Repo Car?

A repo car is a vehicle that has been repossessed by a lender.

This usually happens when the owner stops making loan payments.

The bank or credit union takes the vehicle back and sells it to recover the remaining loan balance.

Banks are not car dealers.

They usually want to sell repossessed vehicles quickly and without hassle. Because of that, repo cars are often priced lower than similar vehicles on dealer lots.


Why Repo Cars Can Be Cheaper

Banks are not trying to make a profit selling repos.

They are simply trying to recover the money that was loaned.

Holding repossessed vehicles costs banks money. They must pay for storage, paperwork, and sometimes transport.

Because of this, banks often price repos to sell quickly.

That is why many buyers search for bank repo cars instead of dealership inventory.


7 Places to Find Repo Cars

Here are the most common places repossessed vehicles are sold.


1. Banks and Credit Unions

Many banks sell repossessed vehicles directly to the public.

Some keep a small list of repos on their website.

Others sell repos locally through word of mouth, sealed bids, internal listings, or auction partners.

This is where RepoFinder.com comes in.

RepoFinder helps buyers find banks and credit unions that are selling repossessed vehicles. Instead of searching dozens of individual lender websites, buyers can start with the free RepoFinder Repo Search tool and search current lender repos by state, vehicle type, keyword, make, model, and price.

From there, buyers can identify available listings and connect with the financial institution selling the vehicle.

This can help buyers find vehicles before they reach auctions or dealership lots, which may mean less competition and fewer middleman markups.


2. Repo Auctions

Auctions are the most well-known place to buy repossessed vehicles.

Banks often send unsold repos to auctions where dealers and the public can bid on them.

Some popular auction options include:

  • Auto auctions
  • Dealer auctions
  • Online auction platforms

The downside is competition.

Many dealers buy inventory from these auctions, which can drive prices higher. Auction buyers may also face bidding rules, buyer fees, transportation costs, and as-is vehicle conditions.


3. Police and Government Auctions

Police departments and government agencies also sell vehicles through auctions.

These may include:

  • Seized vehicles
  • Abandoned vehicles
  • Repossessed property

Some deals can be found, but inventory changes quickly and listings are often scattered across multiple websites.


4. Car Dealerships

Many used car dealerships actually buy their vehicles from repo auctions.

That means some cars on dealer lots started as repossessed vehicles.

The downside is markup.

Dealers must add profit margins, reconditioning costs, and overhead.

That is why buying repos closer to the source can sometimes lead to better deals.


5. Online Marketplaces

Some repos appear on general car marketplaces and classified sites.

These are usually listed by banks, dealerships, or auction resellers.

However, these listings are mixed with millions of regular used cars.

It can be difficult to tell which vehicles are actually repos.


6. Credit Union Listings

Credit unions are one of the most overlooked sources for repo vehicles.

Many credit unions repossess cars and sell them locally to recover their loan balances.

These listings are often posted on small web pages that can be difficult to find through normal searches.

This is another reason buyers use RepoFinder to locate lender repo sources and current repossessed vehicle listings.


7. Specialized Repo Listing Websites

Some websites specialize in tracking repossessed vehicles from banks and lenders.

These platforms gather lender sources and current listings in one place, making it easier for buyers to find vehicles that may otherwise be difficult to locate.

One of the most well-known examples is RepoFinder.com, which focuses on connecting buyers with repossessed vehicles owned by banks and credit unions.

Buyers can use the RepoFinder Repo Search page as a free starting point to search current lender repos by state, vehicle type, keyword, make, model, and price.

This helps buyers locate lender-direct repos that may never appear on a dealer lot or major public auction platform.


Final Thoughts

Repo cars can be one of the best ways to find affordable vehicles.

The key is knowing where to look.

Many buyers only search dealer lots or auction sites.

But banks and credit unions sell repossessed vehicles every day, sometimes before they ever reach those places.

That is why platforms like RepoFinder.com help buyers connect with financial institutions that are selling repos.

To begin, use the free RepoFinder Repo Search tool to search current bank and credit union repos nationwide by state, vehicle type, make, model, keyword, and price.

With a little research and patience, repo vehicles can offer excellent value for buyers looking for their next car, truck, SUV, RV, boat, motorcycle, or other lender-owned asset.

repo cars for sale in California

Bank Repossessed Vehicles Explained | Buy Direct With RepoFinder

TL;DR, The Main Points

  • Banks are emotionless sellers, they do not care about commissions, markups, or negotiation drama
  • A repossessed vehicle is already a loss on a bank’s books, so speed matters more than profit
  • Banks do not upsell, add surprise fees, or play pressure games
  • This creates one of the fairest and cleanest buying environments in the used-vehicle market
  • RepoFinder.com is the best way to find real bank-owned vehicles and contact lenders directly

The Used-Car Market Runs on Emotion

Most people do not realize how emotional the used-car market really is.

Private sellers are emotionally attached to their vehicles.
Dealers are emotionally attached to margins.
Brokers are emotionally attached to commissions.

Everywhere you look, someone has something to defend.

Except banks.

When you buy repo cars for sale directly from a bank or credit union, you are dealing with the only seller in the market that has no personal, emotional, or financial ego tied to the sale.

That single difference changes the entire experience.


What It Means When a Seller Is Emotionless

Calling banks “emotionless sellers” is not an insult. It is an advantage.

Banks do not:

  • Take offers personally
  • Get offended by inspections
  • Argue about sentimental value
  • Push add-ons or upgrades
  • Create fake urgency

They are trying to do one thing only.

Convert a non-performing asset into cash and close the loss.

That clarity removes almost all of the games buyers deal with elsewhere.


Why Repossessed Vehicles Are Already a Loss

By the time a vehicle is repossessed, the bank has already lost money.

That is why pricing is often competitive compared to traditional listings, especially when browsing repo cars near you from local lenders.

The vehicle is no longer a profit opportunity. It is a problem that needs resolution.

That mindset favors buyers.


How Banks Differ From Private Sellers

Private sellers often:

  • Overprice because of attachment
  • Ignore flaws they have learned to live with
  • Take negotiations personally
  • Stall when serious buyers ask questions

Banks do not speak this way.

There is no emotional attachment to defend.


How Banks Differ From Dealers

Dealers operate under constant pressure.

  • Buy low and sell high
  • Protect margins
  • Add fees to stay profitable
  • Upsell to survive

That is why dealer transactions often include extra costs and pressure.

Banks are structured differently.

They are resolving loans, not maximizing retail profit.


Why Banks Do Not Care About Commissions or Fees

This is one of the biggest hidden advantages of buying a bank-owned vehicle.

Banks do not:

  • Pay sales commissions
  • Earn bonuses on higher prices
  • Rely on add-ons

This removes conflicts that exist almost everywhere else in the used-car market.


Policy Replaces Personality

When you buy from a private seller or dealer, you negotiate with a person.

When you buy from a bank, you negotiate with policy.

That is a good thing.

Policy-driven sales mean clear rules, consistent responses, and predictable outcomes.


Why Banks Do Not Care Who Buys the Vehicle

Banks do not care who you are.

They care that:

  • Funds are verified
  • Paperwork is complete
  • The transaction closes

You are not being sold to. You are completing a transaction.


The Hidden Benefit Most Buyers Miss

The biggest advantage of buying from banks is not always price.

It is clarity.

Most used-car frustration comes from noise.

Banks eliminate most of that automatically.


Why Most Buyers Never See Bank Repossessed Vehicles

Access has always been fragmented.

That is why directories that organize banks that sell repo cars are so valuable.

They bring scattered listings into one place.


What RepoFinder Does Differently

RepoFinder exists to solve one problem.

Connecting buyers directly to banks and credit unions selling repossessed vehicles.

You can explore everything from nationwide listings to repo cars for bad credit depending on your situation.


Why Buying Direct Matters

Buying direct means:

  • No middlemen
  • No markups
  • No lead reselling

When you use RepoFinder, you contact the institution that actually owns the vehicle.


Final Takeaway

Banks are the most emotionless sellers in the used-vehicle market.

They care about closing a loss and moving on.

RepoFinder.com makes that rare selling environment accessible by connecting buyers directly to real banks and credit unions.

To start browsing, explore repo cars for sale or check repo cars near you.

a repo car for sale at a credit union

What a Repo Car Really Is

What a Repo Car Really Is (And Why Most “Repo Car” Websites Get It Wrong)

If you search online for a repo car, you’ll see a lot of results.

Auctions.
Salvage cars.
Dealer listings.
“Bank repos” with fees stacked on top.

Here’s the problem:

👉 Most of those aren’t really repo cars anymore.

The word repo gets used loosely online.
Sometimes intentionally.
Sometimes out of confusion.

This article clears that up.

We’ll explain:

  • what a repo car actually is,

  • what it is not,

  • and how to tell the difference before you waste time or money.

No sales pitch.
Just the truth.


What Is a Repo Car? (Plain English)

A repo car is a vehicle that was:

  1. Financed by a bank or credit union

  2. Repossessed after the loan went into default

  3. Still owned by that financial institution

  4. Sold to recover the remaining loan balance

That’s it.

A real repo car is:

  • lender-owned

  • usually clean title

  • priced to liquidate, not maximize profit

Banks are not car dealers.
They don’t want inventory.
They want the loan off their books.

That incentive matters.


Why “Repo Car” Gets Misused Online

The term repo car attracts buyers.

People assume:

  • lower prices

  • cleaner titles

  • fewer games

So a lot of websites use the word even when the vehicle no longer fits the definition.

Let’s look at the most common mix-ups.


Mistake #1: Auction Cars Labeled as Repo Cars

Many vehicles start as repos.

But once a bank sends a vehicle to an auction, it stops being a repo car in the practical sense.

At that point:

  • ownership has changed hands or is in transition

  • auction incentives replace bank incentives

  • fees enter the picture

Large platforms like Copart or brokers like AutoBidMaster sell massive volumes of vehicles.

Some originated as repos.

But buyers are no longer dealing with the lender.

They’re dealing with:

  • auctions

  • brokers

  • bidding systems

  • buyer premiums

That’s a very different transaction.


Mistake #2: Salvage and Insurance Cars Called “Repos”

This one causes the most confusion.

Insurance total-loss vehicles are not repo cars.

They are:

  • accident vehicles

  • flood vehicles

  • hail vehicles

  • theft recoveries

These often carry:

  • salvage titles

  • rebuilt titles

  • or title branding

They can be fine for rebuilders.

But they are not repossessed loan collateral.

Using the word repo here is usually SEO, not accuracy.


Mistake #3: Dealer Cars Marketed as “Bank Repos”

Another common tactic.

A dealer buys a vehicle at auction.
Then relists it as a “bank repo.”

Technically, it once was.

But now:

  • the dealer owns it

  • markup has been added

  • profit is the goal

The bank is gone from the deal.

That distinction matters.


How Real Repossessed Cars Are Actually Sold

When a bank or credit union sells a repo directly, the process looks different.

Usually:

  • no bidding war

  • no buyer premium

  • no middleman fees

You contact the lender.
>You negotiate.
>You inspect.
>You buy.

It’s slower.
Less flashy.
But far more transparent.

And the pricing reflects liquidation, not speculation.


Why True Repo Cars Are Hard to Find Online

This is the core issue.

Banks:

  • don’t market well

  • don’t optimize SEO

  • don’t centralize listings

Each institution handles repos differently.

Some post on their own website.
>Some use PDFs.
>Some rely on internal lists.

There is no single national system.

That’s why buyers end up on auctions instead.

Not because auctions are better — but because they’re louder.


How to Tell If a Website Is Selling Real Repossessed Cars

Use this checklist.

If you answer no to more than one, it’s probably not a true repo sale.

Ask these questions:

  • Do you contact a bank or credit union directly?

  • Is there no bidding involved?

  • Are there no buyer premiums or auction fees?

  • Does the lender still hold the title?

  • Is the vehicle priced to sell, not to extract maximum profit?

Real repo cars feel boring.

That’s a good sign.


Why Title Status Matters

Most bank repos have clean titles.

Why?

Because:

  • they were everyday loan vehicles

  • insured and registered normally

  • repossession doesn’t damage a title

Salvage happens after loss events.

Repos happen after payment defaults.

Different problems.
Different risks.


So Where Should You Look for a Repossessed Car?

If you want:

  • real repos

  • lender-direct pricing

  • fewer games

You need to start at the source.

That means banks and credit unions.

The challenge is finding them all.

That’s where directories exist — not to sell cars, but to point buyers to the lenders themselves.

No auctions.
>No inventory flipping.
>No commissions.

Just access.


The Bottom Line

A repo car is not:

A real repo car is:

Once you understand that distinction, the noise disappears.

And buying gets simpler.


TL;DR

  • “Repo car” is widely misused online

  • Auctions and salvage cars dominate search results

  • True repossessed cars are sold directly by lenders

  • Clean titles and liquidation pricing matter

  • Knowing the difference saves money and time

Car for sale at a local credit union auction

Car Auctions Near Me

Car Auctions Near Me: Why Local Bank & Credit Union Auctions Are the Smart Way to Buy

If you’ve searched car auctions near me, you’re probably tired of dealer prices.

You’re not alone.

More buyers are skipping dealerships and looking for local car auctions instead.
But most people don’t know which auctions are worth their time.

Here’s the truth:

👉 The best car auctions near you are often run by banks and credit unions.

They don’t advertise much.
They don’t hype vehicles.
And they don’t play dealer games.

They just want to sell repossessed cars and move on.

This guide explains why local bank and credit union car auctions are one of the smartest ways to buy a used car.


What “Car Auctions Near Me” Really Means

When people search car auctions near me, they usually want:

What they don’t want is:

  • Salvage cars

  • Dealer-only auctions

  • Hidden fees

  • Mystery damage

Bank and credit union auctions check the right boxes.


What Is a Bank or Credit Union Car Auction?

When someone stops paying on a car loan, the lender repossesses the vehicle.

Once that happens, the bank has one goal:

Recover the loan balance.

They are not trying to maximize profit.
They are not flipping cars.
They are not emotionally invested.

That’s why pricing is often lower and more realistic.

Banks and credit unions sell these vehicles through:

  • Local car auctions

  • Online repo listings

  • Sealed bids

  • Direct bank sales

This is why searching locally matters.


Why Local Bank Car Auctions Beat Dealer Auctions

Dealer auctions are built for volume.

Bank auctions are built for liquidation.

Here’s the difference:

Dealer Auctions

  • Dealer-only access

  • Higher competition

  • Buyer fees

  • Transport costs

  • Often wholesale or salvage

Bank & Credit Union Auctions

  • Many are open to the public

  • Lower starting prices

  • No commissions

  • Local pickup

  • Clean titles are common

If you’re buying one car for personal use, banks win.


Top Benefits of Local Bank & Credit Union Car Auctions

1. Lower Prices Without the Games

Banks price cars based on:

  • Loan balance

  • Vehicle condition

  • Book value

  • Time in inventory

They don’t price cars based on emotion.

That often means thousands less than dealer retail.


2. Vehicles Are Truly Local

Local auctions mean:

  • Local driving conditions

  • Local service history

  • Easier inspections

  • No long-distance transport damage

You’re not buying blind.


3. Clean Titles Are the Norm

Most bank-repo cars were:

  • Daily drivers

  • Properly insured

  • Normally financed

That means clean titles are common.

This is very different from salvage auctions.


4. Less Competition

Large dealers focus on big auctions.

They don’t chase single vehicles from local banks.

That means less bidding pressure for regular buyers.


5. No Dealer Fees or Add-Ons

No forced warranties.
No “reconditioning packages.”
No finance office tricks.

Just a car and a price.


Are Bank Car Auctions Open to the Public?

Yes, many are.

This is one of the biggest myths.

Some banks sell through public auctions.
Others list vehicles directly on their websites.
Some accept sealed bids from anyone.

The challenge isn’t access.

The challenge is finding them.


Why These Auctions Are Hard to Find

Banks are not marketers.

They don’t care about SEO.
They don’t run ads.
They don’t optimize Google listings.

Their repo cars are often hidden on:

  • Individual bank websites

  • Credit union pages

  • Old PDFs

  • Broken links

That’s why most people never find them.


How RepoFinder Makes It Easy

RepoFinder solves this problem.

RepoFinder connects buyers directly to:

  • Local banks

  • Credit unions

  • Their actual repo listings

No fees.
No commissions.
No middlemen.

Just real lenders selling real vehicles.


What Cars You’ll Find at Local Bank Auctions

Most local bank auctions include:

  • Sedans

  • SUVs

  • Pickup trucks

  • Vans

Most vehicles are:

  • 1–8 years old

  • Normal mileage

  • Clean title

  • Sold as-is

They aren’t perfect.

They’re honest.


How the Buying Process Works

Most bank auctions follow this simple process:

  1. Vehicle is repossessed

  2. Condition is documented

  3. Price or bid terms are set

  4. Listing is published

  5. Buyer inspects

  6. Sale completes

  7. Title transfers

No drama.


Can You Inspect the Car First?

Often, yes.

Many banks allow:

  • In-person inspections

  • Limited test drives

  • Third-party inspections

Local matters here.

Inspection is much easier when the car is nearby.


Common Buyer Mistakes

Mistake #1: Assuming “Auction” Means Salvage

Bank auctions are different.

Mistake #2: Skipping the VIN Report

Always check Carfax or AutoCheck.

Mistake #3: Forgetting Taxes and Registration

Banks sell the car.
You handle the rest.

Mistake #4: Waiting Too Long

Good repo cars sell fast.


Are There Risks?

Yes, but they’re manageable.

Possible Downsides

  • Sold as-is

  • No warranties

  • Limited returns

How to Reduce Risk

  • Inspect carefully

  • Research market value

  • Ask questions

The risk is often lower than buying from a used car lot.


Why “Car Auctions Near Me” Is the Right Search

The keyword isn’t wrong.

The results usually are.

Most sites that rank are:

  • Dealer auctions

  • Salvage platforms

  • Middlemen

The real deals are local.

And they come from banks.


FAQ: Car Auctions Near Me

Are bank car auctions legit?

Yes. Banks are regulated lenders selling repossessed vehicles.

Do bank auctions sell clean title cars?

Most do. Salvage titles are less common.

Can anyone buy from a bank car auction?

Many are open to the public. It depends on the lender.

Are prices really lower?

Often, yes, because banks want loan recovery, not profit.

Do I need cash?

Some require certified funds. Others allow normal payment methods.

Is RepoFinder an auction site?

No. RepoFinder connects buyers directly to banks and credit unions.


Final Takeaway

If you’re serious about saving money, local bank and credit union car auctions are one of the smartest options available.

They offer:

  • Lower prices

  • Clean titles

  • Local vehicles

  • Less competition

  • No dealer games

And when you know where to look, they’re easy to find.

That’s the difference between searching car auctions near me and actually buying smart.

Comparison of where to find repossessed cars auctions banks dealers online repos US

Where to Find Repossessed Cars, Auctions, Banks, Dealers, Online, Repos US

This entry was posted in Blog and tagged , , , on by .

If you’re searching for repo cars near me, you’re not alone. Thousands of buyers are looking for affordable vehicles sold directly by banks and credit unions.

These repossessed vehicles are often priced below traditional dealership listings because lenders are focused on recovering loan balances, not maximizing profit.

With the right approach, you can find reliable vehicles in your area and avoid dealer markups entirely by browsing repo cars for sale directly from financial institutions.


What Are Repo Cars?

Repo cars, or repossessed vehicles, are cars that lenders take back when borrowers stop making payments on their loans.

Once repossessed, these vehicles are typically resold by the bank or credit union to recover the remaining balance.

Many of these vehicles are in good condition and can be purchased at competitive prices compared to traditional used car listings.


Where to Find Repo Cars Near You

The biggest challenge is not understanding repo cars, it is knowing where to find them.

Most banks do not advertise heavily, and their listings are spread across hundreds of different websites.

That is why many buyers use directories that organize banks that sell repo cars in one place.

This allows you to quickly locate local listings without searching dozens of individual bank websites.

You can also browse repo cars near you to find vehicles available in your area right now.


Why Repo Cars Are Often Cheaper

Unlike dealerships, banks are not trying to maximize profit on each vehicle.

Their goal is to recover loan balances quickly.

This often results in:

  • Lower listing prices
  • No dealer commissions
  • No retail markups
  • Faster sales process

This pricing structure is what makes repo vehicles appealing to budget-conscious buyers.


Types of Repo Vehicles Available

Repo listings are not limited to just cars.

You can often find:

  • Sedans and compact cars
  • SUVs and crossovers
  • Pickup trucks
  • Motorcycles and powersports
  • RVs and boats

Inventory changes frequently, so checking listings regularly can help you find better deals.


Can You Buy Repo Cars With Bad Credit?

Yes, in many cases you can.

Some banks offer financing options on repossessed vehicles, even for buyers with less-than-perfect credit.

If you are in this situation, you can explore repo cars for bad credit to see available options.


Tips for Buying Repo Cars Near You

  • Research the vehicle before purchasing
  • Inspect the car if possible
  • Compare prices with similar listings
  • Contact the lender directly for details

Taking these steps can help you avoid common mistakes and find better deals.


Final Thoughts

Finding repo cars near you is one of the best ways to save money on a vehicle.

By working directly with banks and credit unions, you can avoid dealer markups and access inventory that many buyers never see.

To get started, browse repo cars for sale or explore repo cars near you to find available vehicles in your area.

repo car for sale at a credit union

What Is a Repo Car?

If you search online for “repo cars,” you’ll find everything from clean-title bank vehicles to heavily damaged insurance write-offs mislabeled as repos. The result is a confusing marketplace where many buyers struggle to tell the difference between true repossessed vehicles and cars that simply use the word “repo” as a marketing hook.

This guide breaks through that noise with a clear definition of what a repo car actually is, how it differs from salvage and government-seized vehicles, and why true bank repos often represent some of the best-value used-car purchases available today.

Whether you’re researching your first repo purchase or strengthening your consumer education strategy, this article gives you an authoritative foundation. If you want to see real inventory while you read, start with repo cars for sale or browse repo cars near you.


What Is a Repo Car?

A repo car is a vehicle that has been repossessed by a bank, credit union, or financial institution because the borrower defaulted on the loan.
That’s it. No accident, flooding, insurance claim, or structural failure.

✔ The key point:

Repo cars are generally clean-title vehicles where the only “problem” is that someone stopped making their payments.

Why is this important?

Because a clean title and normal usage history make repo cars fundamentally different from salvage vehicles, flood-damaged cars, and government-seized vehicles. In the purest form, a bank repo is a mechanically sound, street-legal vehicle that went unpaid, not a vehicle that has been written off or recovered after significant damage.

Financial institutions are not in the automotive business. When a default happens, they repossess the vehicle, secure it, inspect it, and make it available for resale, typically without dealer markups, buyer fees, commissions, or hidden middlemen.

This is why many banks list their repos directly or partner with directories that help buyers find banks that sell repo cars without additional layers of cost.


Why Repo Cars Are Generally Clean Title Vehicles

When a vehicle is repossessed, the bank expects the vehicle to be resold quickly. Unlike insurance companies, banks do not brand titles unless required by law. If a repo vehicle had a clean title before the borrower defaulted, it will almost always remain a clean title when the bank resells it.

A bank has no incentive to alter the title status because the underlying issue is financial, not mechanical.

Common misconceptions:

  • ✔ “A repo car must have problems.”
    Not necessarily. Millions of repos happen each year due to financial hardship, job loss, divorce, or unexpected medical expenses, not because the vehicle was unsafe.
  • ✔ “A repo car is risky.”
    Repo cars typically receive an inspection or condition report, and the bank has no incentive to hide issues. They simply want to recover the remaining loan balance.

If you want a deeper explanation of clean titles, see our internal guide:
👉 Understanding What a Clean Title Means


How Repo Cars Differ From Salvage Cars

This is the area where most consumers get misled, and where salvage-auction marketing creates confusion on purpose.

A Salvage Car Is NOT a Repo Car

A salvage vehicle is a vehicle that has been declared a total loss by an insurance company because of:

  • collision damage
  • flood or fire damage
  • hail destruction
  • theft recovery
  • repair costs exceeding a certain percentage of value

Salvage cars typically go through dealer-only auctions such as Copart or IAAI, where they are sold “as is” with varying levels of damage.

Why the distinction matters

A true repo is taken for non-payment.
A salvage vehicle is taken because it was deemed unsafe or uneconomical to repair.

They are not the same.


The Salvage Industry and the Hijacking of the Word “Repo”

In recent years, some salvage sellers and auction platforms have begun labeling severely damaged vehicles as “repos” to attract buyers who associate repos with clean-title bargains. This is misleading at best, and intentionally deceptive at worst.

Examples of misleading usage you may see:

  • “Finance Repo” slapped onto a flood-damaged car
  • “Bank Repo!” describing a hail-total loss
  • “Repossession Sale!” for a theft-recovered vehicle with a salvage title
  • “Repo blowout!” for insurance write-offs
  • “Recovered Repo” for a fire or collision loss

None of these are actual repossessions by a lender.

Why the salvage industry misuses the term

Because “repo car” signals value, while “salvage” signals risk.
If a platform sells mostly salvage vehicles, rebranding them as “repo” increases traffic and conversion at the expense of buyer clarity.

Why this matters for consumers

When buyers confuse salvage vehicles with bank repos, they assume:

  • the vehicle has a clean title
  • the price reflects normal market value
  • financing may be available
  • there are no structural or mechanical issues

But salvage vehicles often need substantial repairs, may not pass safety inspections, and may be impossible to finance through traditional lenders.

This article aims to correct that industry-wide confusion.


Repo Cars vs. Government-Seized Vehicles

Government-seized cars enter the market for completely different reasons and through completely different buying channels.

What is a government-seized car?

A vehicle confiscated by:

  • U.S. Marshals
  • IRS
  • DEA
  • Local police departments
  • Homeland Security
  • Customs and Border Protection

These vehicles may come from criminal investigations, unpaid taxes, smuggling operations, or assets seized under forfeiture laws.

Why they are not repo cars

Repo cars are repossessed by lenders for loan default.
Government-seized cars are taken by authorities as legal evidence or assets.

Can government-seized cars be good deals?

Yes, but with important caveats:

  • ✔ Buying processes vary by agency, auction type, and location.
  • ✔ History may be unknown, especially if the vehicle was abandoned or seized during an arrest.
  • ✔ Damage is common, especially interior wear, storage damage, or neglect.
  • ✔ Condition reports may be limited or inconsistent.

In contrast, bank repos are much more predictable, clean titles, normal usage history, and standardized sale procedures.


How True Bank Repos Are Sold

Banks have no desire to store cars. Their goal is to:

  1. Recover the unpaid loan amount
  2. Avoid fees and commissions
  3. Sell the vehicle as efficiently as possible

Where bank repos typically get sold:

  • Directly on their website
  • Through local credit-union listings
  • Through regional lending associations
  • Through platforms that aggregate bank and credit union repo links
  • Occasionally through dealer-only auctions, which are not consumer-friendly

Why direct-bank repos offer the best value

No middleman.
No commissions.
No buyer fees.
No hidden markups.

When you buy directly from a lender, the price you pay is the price the bank wants for the asset, not an inflated reseller price. That is why many buyers start with repo cars for sale or use repo cars near you to narrow the search by location.

Real-World Example:

  • Many credit unions and banks in the United States list repos directly on their websites.
  • Some of these list:
    • a 2021 Honda Accord with a clean title
    • priced below book value
    • inspected, detailed, and ready for sale
    • financing available through the same credit union

This is fundamentally different from a salvage auction selling a total-loss vehicle misbranded as a “repo.”


Why Repo Cars Offer Exceptional Value

1. Clean Title Advantage

Because repos are not insurance write-offs, most maintain a clean title, meaning fewer legal and mechanical unknowns.

2. Lower Prices Without Dealer Add-Ons

Banks don’t add:

  • documentation fees
  • dealership markups
  • auction buyer premiums

You often negotiate directly with the institution.

3. Potential for Low-Rate Financing

Some lenders even offer special interest rates on their own repos to encourage purchases and clear inventory.

Buyers who need flexible financing can also compare repo cars for bad credit to see what lenders offer in different situations.

4. Transparent Process

Unlike seized-vehicle auctions or salvage platforms, banks typically provide:

  • inspection reports
  • photos
  • maintenance notes when available
  • simple offer forms

This creates a more predictable buying experience.

5. No Emotional Seller Factors

Private-party sellers may hide issues. Banks do not. They simply want the asset sold.


Where Buyers Can Find Legitimate Repo Cars

The best sources are always banks and credit unions. Some buyers prefer to check:

  • Local credit-union websites
  • State lending associations
  • Banks that publish repos quarterly
  • Regional financial cooperatives

To streamline this process, platforms like RepoFinder organize these links by state and institution, helping buyers navigate directly to the repossession inventory rather than wading through salvage marketing tactics.

A good next step is to browse banks that sell repo cars so you can see who actually owns the vehicle before you shop.


Common Myths About Repo Cars

Myth #1: Repo cars have bad engines or major issues.

Reality: Most repos were daily drivers before a financial hardship.

Myth #2: Repo means “damaged.”

Reality: Repo means loan default, not accident, fire, or flood.

Myth #3: Repos are the same as seized cars.

Reality: Completely different categories, histories, and auction processes.

Myth #4: Repo cars come from shady sources.

Reality: Most come from reputable banks and regulated financial institutions.


How to Verify You’re Looking at a Real Repo Car

Here’s a simple checklist:

  • ✔ Listed by a bank or credit union
  • ✔ Clean-title status
  • ✔ No insurance company involvement
  • ✔ Price aligns with market value
  • ✔ Listing includes a neutral inspection report
  • ✔ No “salvage,” “rebuilt,” “flood,” or “total loss” language

If a seller uses the word “repo” but the vehicle carries a salvage title, or the photos show obvious damage, you’re likely looking at a misleading listing.


Why Salvage Vehicles Should Not Be Marketed as Repo Cars

This is worth stating clearly:

A salvage vehicle is not a repo vehicle in any sense of the term.

When platforms blur the distinction, consumers lose:

  • transparency
  • trust
  • safety confidence
  • financing options
  • resale value

This misuse of the term “repo” harms buyers and inflates expectations. Clarifying that difference helps consumers make better decisions and protects the integrity of true bank-repo markets.


Final Thoughts: Repo Cars Are Some of the Best Deals in Today’s Used-Car Market

A repo car is simple to define:

A clean-title vehicle repossessed due to unpaid loans, not because of damage, insurance claims, or accidents.

This makes repo cars fundamentally different from:

  • salvage vehicles
  • rebuilt-title cars
  • totaled vehicles
  • government-seized cars

Banks and credit unions favor fast, transparent sales, which means the buyer often benefits from lower prices, no middlemen, and no hidden fees.

If you want to explore real, verified bank and credit-union repo listings, start here:

Browse repo cars for sale, find repo cars near you, or view banks that sell repo cars.

repo car for sale at a credit union in Texas where people are Bidding on Repo Cars

Step-by-Step Guide to Bidding on Repo Cars at Auctions

Step-by-step guide to bidding on repo cars at auctions

Bidding on repo cars from a bank can feel confusing.
Many people think they must use big “repo auctions” online.
That is not actually true.

There is a better way.
You can buy true repossessed cars directly from banks and credit unions.
You can do this without middlemen, games, or hidden fees. A simple way to start is by browsing repo cars for sale directly from lenders before jumping into auctions.

This guide walks you through that process step by step.
You will also see how RepoFinder helps you find these cars fast.


What is a true bank repo car?

A repossessed car is a vehicle a bank took back for non-payment.
The borrower missed too many payments on the loan.

The bank does not want the car long term.
It only wants to recover as much of the loan as it can.

A true bank repo car is:

  • Taken back by a bank or credit union

  • Usually a clean title vehicle

  • Sold to reduce the bank’s loss, not to make a profit

Banks are not car dealers.
They do not need extra profit from the sale.
In fact, they expect to lose money on most repossessions.

If they send a car to a dealer auction, they may get only a fraction of value.
So they often prefer to sell it themselves to the public.


Why you must not confuse repo cars with salvage cars

Many shoppers search for “repo auctions” online.
They often land on salvage auctions instead.

This is a huge problem.

Salvage auctions usually sell:

  • Insurance total loss vehicles

  • Flood, fire, or severe collision damage cars

  • Cars that now carry a branded title, not a clean title

These are not the same as true bank repos.

Why salvage or branded title cars are risky

  • They may have hidden structural damage.

  • Future repairs can be very expensive.

  • Safety can be reduced in a future crash.

  • Many buyers and lenders avoid them.

This also hurts resale value.
Branded title cars often sell for much less later.

When you buy from a bank’s repo list, you are usually getting a clean title car.
You avoid many of the dangers that come with salvage or rebuilt vehicles.


Why banks sell repo cars cheaply

Banks and credit unions are in the money business.
They are not in the car selling business.

When a car is repossessed, the bank:

  1. Already lost time and money on missed payments.

  2. Must pay storage, insurance, and handling costs.

  3. Wants the car gone from its books as soon as possible.

Every week that car sits, the bank loses more money.

So the bank’s main goals are simple:

  • Sell the car quickly

  • Recover as much of the loan as possible

  • Move on to regular banking business

The bank is not trying to “squeeze” you like a dealer might.
It just wants a reasonable offer and a clean, fast sale.


How banks usually take bids on repo cars

Most banks use a simple bid process for repo cars.

Common methods include:

  • Highest bid wins:
    They collect offers until a deadline.
    Then they accept the best reasonable offer.

  • “Buy it now” price:
    They list a firm asking price.
    You can offer to pay that price and end the process.

Sometimes they use both.
They may list an asking price but still accept bids below that.

Remember, the bank is not required to accept every offer.
It will compare each bid with the car’s value and the loan balance.


Why RepoFinder is useful in this process

True bank repo cars can be hard to find alone.
Each bank or credit union often lists its own vehicles.
Links can be buried deep on their websites.

RepoFinder has done the hard work for you since 2009.

RepoFinder:

  • Lists banks and credit unions across the country

  • Links you directly to their repo pages

  • Focuses on true repossessions, not salvage auctions

  • Is free to use for shoppers

You are not bidding on RepoFinder itself.
You use RepoFinder to find the bank or credit union that owns the car.
Then you deal with that lender directly.


Step-by-step guide to bidding on bank repo cars

Step 1: Use RepoFinder to locate bank repo cars

Start at RepoFinder.com.

  • Choose your state or nearby states.

  • Browse the list of banks and credit unions.

  • Click through to their repo or “for sale” pages.

You will see various vehicles.
These may include cars, trucks, SUVs, RVs, and more.

Focus only on vehicles listed as repossessed or “bank owned.”


Step 2: Check the basic details and title status

Click on a vehicle that interests you.

Look for:

  • Year, make, and model

  • Mileage

  • Basic options and trim

  • Asking price or starting bid

  • Title status information

If the listing does not clearly state title status, ask the bank.
You want to confirm that it is a clean title, not salvage or rebuilt.

If the title is anything other than clean, think very carefully.
Most buyers should avoid these cars for safety and resale reasons.


Step 3: Run a vehicle history report

Before you bid, get the VIN from the listing.

Use the VIN to run a vehicle history report.
This can reveal:

  • Past accidents

  • Title changes or branding

  • Odometer issues

  • Previous owners and locations

If you see major accidents or flood damage, move on.
There are many other bank repos that may be cleaner.


Step 4: Inspect the car in person when possible

Whenever you can, see the vehicle in person.

Ask the bank:

  • Where the car is stored

  • When you can view it

  • Whether you can bring a mechanic

If they allow it, bring a trusted mechanic or knowledgeable friend.

Check:

  • Body and paint condition

  • Frame and undercarriage rust or damage

  • Tires and brakes

  • Engine noise, leaks, and smoke

  • Transmission shifting and test drive feel

If a test drive is not allowed, at least start the engine.
Listen for odd knocks, rattles, or warning lights.

Take photos and notes.
Compare the car’s condition with its price and book value.


Step 5: Talk to the bank about how bidding works

Next, speak with the bank’s contact person.

Ask clear questions like:

  • “How do you accept offers or bids?”

  • “Is there a minimum bid or reserve price?”

  • “Is there a deadline for offers?”

  • “Do you have a ‘buy it now’ price?”

  • “How will you notify me if my bid wins?”

Get these details before you submit your offer.
This prevents confusion later.

Remember, banks often collect multiple bids.
They usually accept the highest reasonable offer that meets their internal target.


Step 6: Ask about special bank repo financing

Here is a big advantage many people miss.

Because the bank already owns the car, it may offer special financing.
Sometimes, this can be as low as one percent interest for a well-qualified buyer.

Why would the bank do that?

  • You are helping remove a bad loan from their books.

  • They can turn a non-paying loan into a new, current loan.

  • They keep you as a happy new customer.

Ask questions like:

  • “Do you offer special financing if I’m bidding on repo cars?”

  • “What is the lowest interest rate available?”

  • “What are the terms and required down payment?”

Do not assume the bank rate is high.
In many repo cases, the rate is better than typical dealer financing.


Step 7: Decide your maximum bid or offer

Based on your research, set a maximum price in your mind.

Consider:

  • Book value for a clean title, similar mileage car

  • Any repairs needed now or very soon

  • Taxes, registration, and insurance

  • Your personal budget

Never bid more than your maximum.
It is easy to get caught up in winning.
Remember, you want a good deal, not just a win.


Step 8: Submit your bid or buy-it-now offer

Now you are ready to bid.

Follow the bank’s instructions exactly.
They may ask you to:

  • Fill out a bid form

  • Email your offer

  • Deliver a sealed bid to a branch

  • Place a bid through an online form

Include:

  • Your full name and contact information

  • The vehicle details and VIN

  • Your offer amount

  • Any conditions, like required inspection or financing approval

If the bank has a “buy it now” price you like, you can offer that amount.
This can beat other bidders instantly.


Step 9: Wait for the bank’s decision

After bids close, the bank will review the offers.

This process may take a few days.
They will choose the best offer based on price and the buyer’s strength.

If you win, they will contact you with next steps.
If you do not win, stay polite and thank them.
You can always bid on another vehicle later.


Step 10: Complete financing and paperwork

If your bid is accepted, move quickly.

You will usually need to:

  • Sign a purchase agreement or bill of sale

  • Finalize your loan with the bank or your own lender

  • Provide proof of insurance

  • Pay any required fees and taxes

The bank will then sign over the title to you.
Make sure the title status matches what you were promised.

Keep copies of all documents for your records.


Step 11: Take delivery and enjoy your new car

Finally, schedule pickup of the vehicle.

Inspect it again when you arrive.
Confirm that nothing has changed since your earlier visit.

  • Once you are satisfied, drive it home.
  • You now own a repo car bought directly from a bank.
  • You’ve avoided dealer games.
  • You also avoided risky salvage auctions.
  • You’ve likely saved a lot of money in the process.

Common questions about bidding on bank repo cars

Are repo cars always in bad shape?

No.
Some are rough, but many were daily drivers.
They often ended up as repos due to money problems, not abuse.

Always inspect each car on its own.


Can I get a warranty with a repo car?

Usually, repo cars are sold as-is.
That means no warranty from the bank.

You can ask about buying an extended warranty from a third party.


Do I need cash to buy a bank repo car?

Not always.
Many banks and credit unions offer financing on their own repos.
This may include special low rates, sometimes around one percent.


Is it safe to bid on repo cars online?

It can be safe if you know the bank is real.

Use RepoFinder to reach actual banks and credit unions.
Avoid random sites that mix in salvage auction cars.


Why are bank repo cars harder to find than salvage auction cars?

Banks do not spend much on marketing.
They post repos on their own websites, but usually not on giant ad platforms.

RepoFinder brings these scattered links together in one place.


Final tips when bidding on repo cars

  • Only buy clean title vehicles when possible.

  • Never confuse bank repos with salvage auction cars.

  • Use RepoFinder to find real banks and credit unions.

  • Inspect each car and run a history report.

  • Ask about special repo financing.

  • Set a firm maximum bid and stick to it.

With a little patience, you can get a safe, clean title car at a strong price.
You also help a bank cut its losses and move forward.

That is a win for both sides.

repo car sold cheaper directly by a credit union

Are Repo Cars Cheaper? A Clear, Expert Answer

If you’ve ever wondered whether repo cars are actually cheaper than buying from a dealer, the short answer is yes — and usually by a wide margin.

As the team behind RepoFinder since 2009, we’ve seen tens of thousands of pure bank and credit-union repos move across the market. And after decades of tracking pricing, buyer behavior, and bank liquidation patterns, we can say with confidence:

True repos sold directly by banks are consistently cheaper than dealer retail, auction listings, or anything advertised as a “repo” by salvage sites.

Below is a fast, skimmable expert breakdown based on our firsthand experience.


Why Repo Cars Are Cheaper

1. Banks aren’t dealers — they don’t need profit margins

Banks don’t sell cars for a living.
When they repossess a vehicle, it becomes a hot potato on their books. Every day it sits, they lose money.

This is why:

  • Banks expect to sell below book value

  • They avoid commissions and fees

  • They prefer fast, clean liquidation over squeezing for every dollar

In contrast, auctions and dealers depend on markups and fees to survive.


2. Banks get more selling directly than dumping cars at auction

If a bank sends a car to auction, they may recover only 25–30% of its real value.
When they sell it themselves:

  • No auction fees

  • No commissions

  • No dealer cuts

They keep more — and you pay less.

This is why direct bank sales, the pure repos we list on RepoFinder, are some of the best values in the used-car market. You can browse current repo cars for sale or start with our directory of banks that sell repo cars.


3. True repos keep their clean titles

Almost all true bank repos we see:

  • Are under 6–7 years old

  • Have clean titles

  • Often still have factory warranty coverage

  • Are repossessed only for financial reasons, not damage

Banks cherry-pick the clean, desirable cars to sell themselves.
If a vehicle is severely damaged, many banks do send it to a salvage auction instead.

That’s why RepoFinder buyers overwhelmingly get clean-title cars. If you want a deeper breakdown, see do repo cars have clean titles.


The Biggest Misconception: “Repo” vs. Salvage Auctions

Many shoppers think “repo” means damaged or abused.
This misconception comes from salvage auction companies who hijacked the keyword.

When you Google “repo cars,” here’s what you usually get:

  • Salvage auction sites

  • Insurance write-offs

  • Dealer-only auctions

  • Total loss vehicles

  • Cars branded clean… until registration

These are not the pure repos banks sell.

We’ve seen countless Reddit posts where buyers thought they scored a cheap “repo” at an auction — only to discover the title branded after they registered it.

That never happens with true bank repos.


Real-World Price Example (We Watched This Happen)

One of the biggest deals we’ve tracked was a late-model Mercedes gull-wing sports car:

  • Original MSRP: $130,000+

  • Bank’s asking price after it sat awhile: $60,000

  • Low miles, clean title, great condition

It sold for less than half its real retail value simply because:

  • It was a niche car

  • Fewer eligible buyers

  • The bank didn’t want to sit on it

  • The longer it sits, the more they lose

We see price drops like this weekly — especially on specialty vehicles, boats, and higher-end models.


What Types of Repo Cars Are Cheapest?

Based on 16 years of tracking pure bank repos:

  • Common cars & trucks → reliably discounted

  • Older, low-mile vehicles → sometimes under $1,000

  • High-end luxury cars → massive discounts when they sit

  • Boats, ATVs, RVs → deep cuts when seasonal demand is low

  • Rare/specialty vehicles → biggest drops due to limited buyer pools

Buyers patient enough to watch listings for a few weeks often snag incredible deals. If price is your top priority, start with cheap repo cars and compare local inventory too.


Do Banks Negotiate? Almost Always.

In nearly every repo transaction we’ve observed:

  • Banks negotiate price

  • Banks negotiate financing

  • Banks negotiate interest rates

We’ve even seen banks drop interest rates to 1% on repo purchases because, in their eyes, selling the car is doing them a favor.

And yes — every bank we’ve ever seen allows inspections, including test drives, mechanic checks, and on-site evaluation.

Not one bank in 16 years has ever refused.


The #1 Mistake Buyers Make

Believing that all “repo” cars online are equal.

If it’s not:

  • Sold by a bank

  • Listed on a bank’s site

  • Stored at a bank

  • Priced by a bank

…then someone else already took the profit out of the deal.

Dealers, wholesalers, and salvage auctions use the word “repo” as bait
— even when the car is actually a salvage title, insurance loss, or dealer-purchase.

True repos come only from banks and credit unions. That’s why buyers should begin with real banks that sell repo cars, not recycled auction inventory.


Who Gets the Best Value With Repo Cars?

From our experience, repo buyers tend to fall into these groups:

  • Families watching every dollar

  • First-time car buyers

  • Bargain hunters

  • Tradespeople who value reliability

  • Flippers and small dealers

  • Anyone willing to be flexible on color/trim

Many car dealers use RepoFinder to build inventory — because they know exactly where the real deals are.


Why Repo Cars Are Cheaper — One Sentence

Repo cars are cheaper because you’re buying them directly from a bank that has no interest in holding or profiting from vehicles.


So… Are Repo Cars Cheaper? Absolutely. And Here’s Where to Start.

For buyers willing to step slightly outside the dealership system, repo cars offer:

  • Better pricing

  • Cleaner titles

  • Newer inventory

  • Less pressure

  • Transparent inspections

  • Optional bank financing

  • No commissions or dealer markups

And because we’ve been doing this since 2009, we’ve made RepoFinder the easiest way to find pure, direct-from-bank repos without the salvage auction noise.


Looking for a True Repo – Not a Salvage Auction?

If you want to browse real repos from banks and credit unions — the kind that stay under book value and keep clean titles — you can start right here with us at RepoFinder.

We link you directly to the banks. No middlemen. No commissions. Just real repos.

Start here: repo cars for sale, repo cars near you, or banks that sell repo cars.